
Sep. 22, 2026

5 Min read

Loan

Share :


Every loan has a distinct lifecycle: why you borrow, where the capital goes, and how you service the EMIs. While business loans and personal loans often sit side by side on financial portals, treating them as interchangeable is a common mistake. In reality, how they function, what they cost, and who qualifies for them could not be more different.
Choosing the right loan can help you get the best interest rates and keep your business and personal finances separate.
So where does a business loan actually differ from a personal loan? Well, it honestly depends on what the money is for. You take out a business loan, and its whole purpose is to keep a company functioning, restocking inventory, getting new equipment on the floor, hiring staff, opening in another city, or just plugging a working capital hole: a gap when a month runs slow. The lender wants that money to go to the right place. They want it to be used in the business again, not left sitting around.
Unlike commercial borrowing, personal loans carry zero end-use restrictions. Whether you are managing unexpected hospital bills, funding home repairs, or planning a major life event, the capital is yours to use as needed. Choosing between a personal and a business loan isn’t about which product is better overall but rather which one directly aligns with your specific funding needs.
| Feature | Business Loan | Personal Loan |
| Main purpose | Business growth, operations, expansion | Any personal expense |
| Collateral | Can be secured or unsecured | Mostly unsecured |
| Tax benefit | Interest often counted as a business expense. | Usually no tax benefit |
| Loan amount | Generally higher, based on business profile | Generally lower |
| Repayment tenure | 104 Days – 373 Days | 24 Months – 36 Months |
Ask any owner who’s scaled past the early years, and they’ll usually tell you the same thing: mixing personal money with business money gets messy fast. This is part of why entrepreneurs prefer business loans over personal loans so often.
Personal loans also have their own advantages, but for different reasons. They’re built for speed and simplicity.
One thing worth remembering, though, is that fast doesn’t always mean cheap. Occasionally it’s the opposite.
Since most personal loans are unsecured, lenders build extra risk into the pricing. A typical personal loan interest rate starts somewhere around Min 18% – Max 24% per annum scale significantly higher, depending on your income, employer, credit history, and how consistently you’ve repaid debt before. Your credit score does a lot of the talking here.
A business loan interest rate, on the other hand 28% (Annualized Basis), simply because a business loan isn’t one single product. Unsecured business loans typically land in a wider range, while secured business loans, backed by property or machinery, usually come with noticeably lower rates
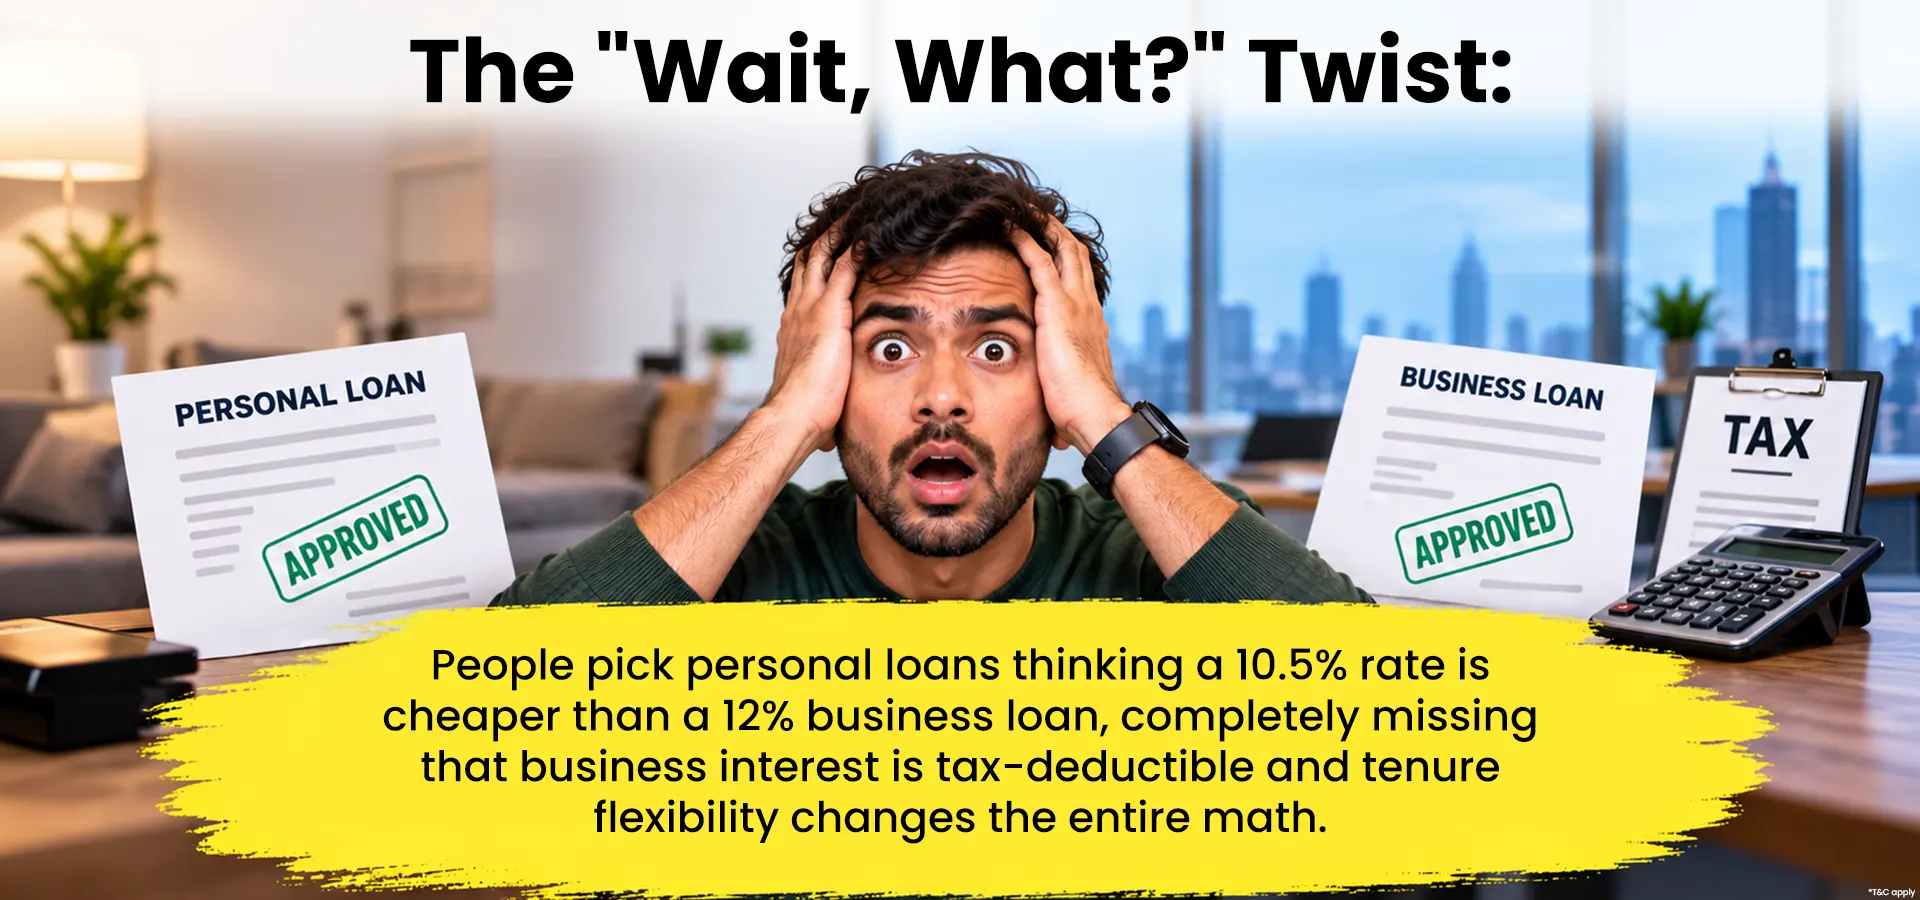
This factor also feeds into repayment terms. If you qualify for a secured business loan, you can often stretch repayment out over 104 Days – 373 Days , sometimes matching long-term secured products. Personal loans rarely offer that kind of runway; most cap out at a handful of years, which means higher EMIs over a shorter window.
Lenders don’t approve loans on gut feeling; they run through a checklist, and that checklist changes based on what you’re applying for.
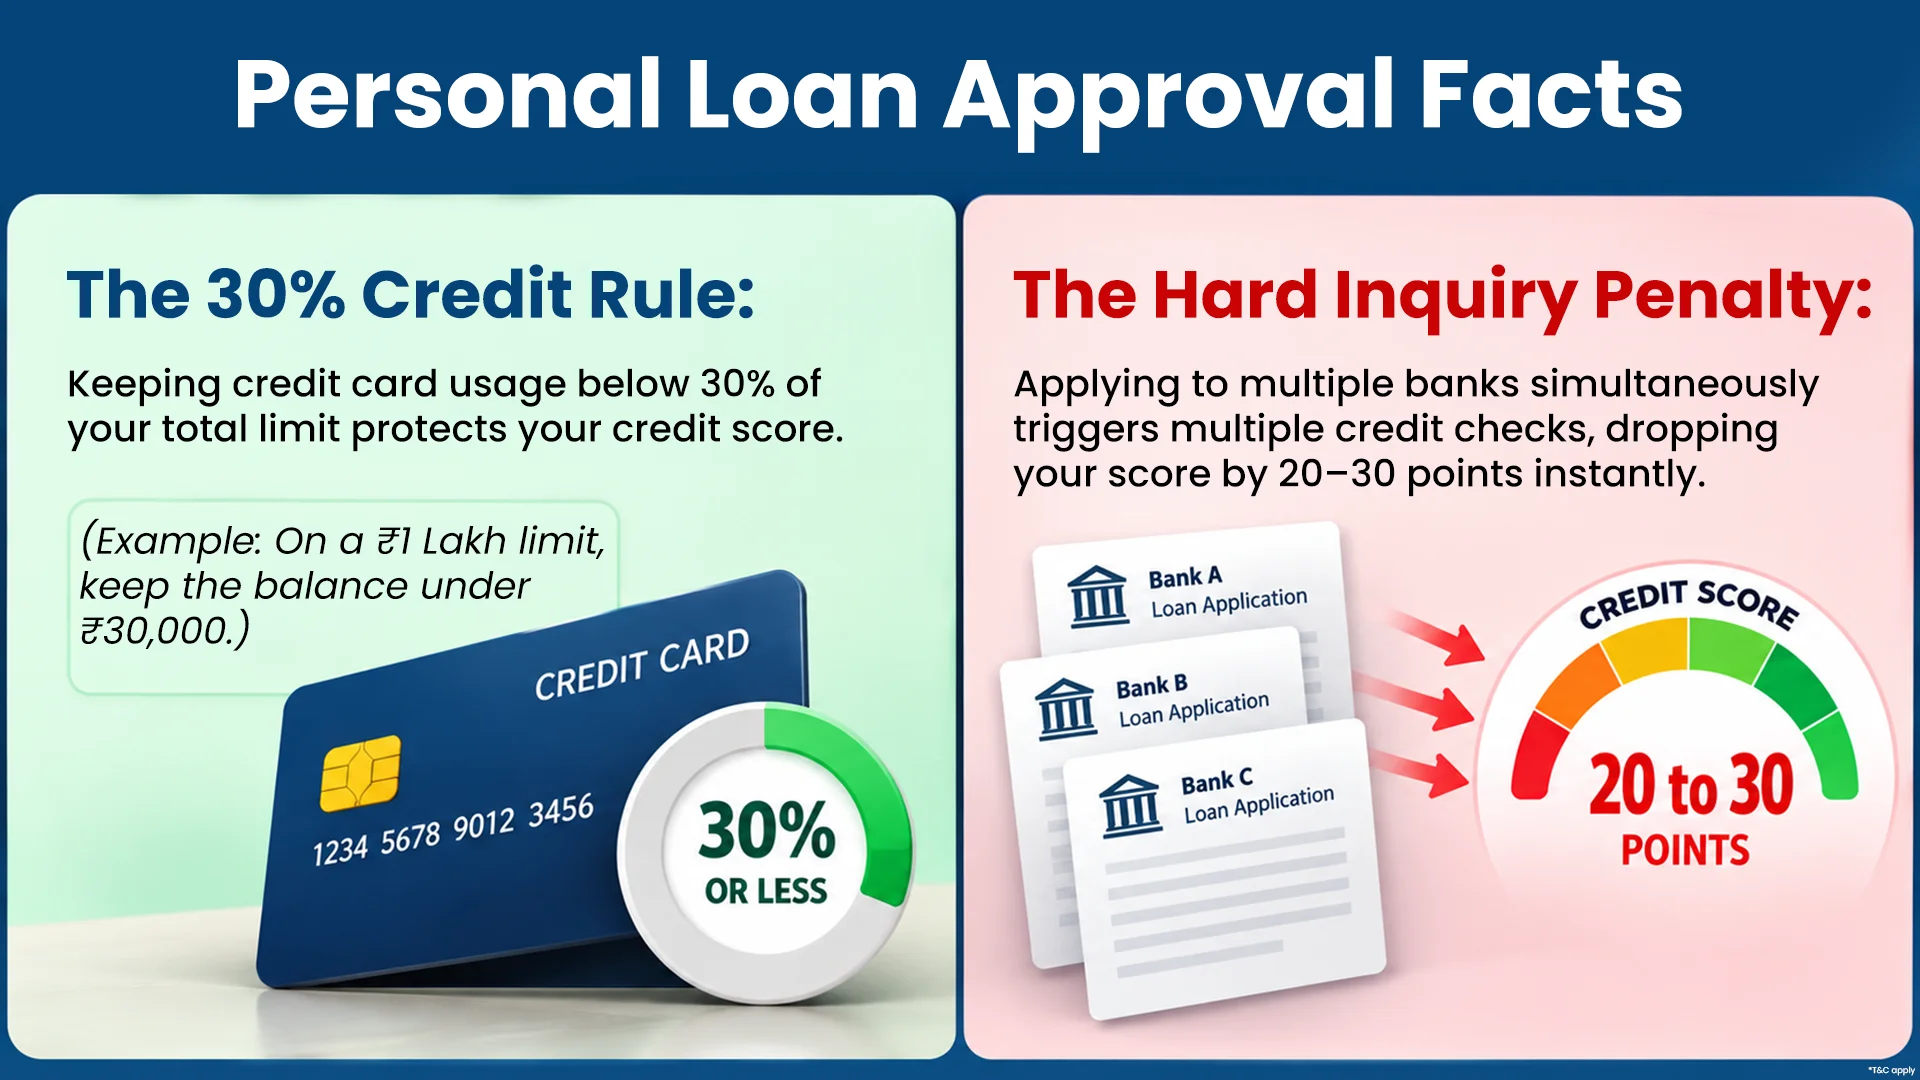
If your cash flow looks inconsistent on paper, be prepared for delays, additional questions, or less favourable terms.
If you’re building a business, trying to grow revenue, and want to make the most of tax benefits, a business loan is usually the smarter tool, especially when you can secure it and stretch the tenure out. If you’re facing a short-term personal expense and want the least amount of friction, a personal loan will likely get you the money faster with far less paperwork.
Neither one is universally better; both business loan benefits and personal loan benefits matter depending on the situation you’re actually in. Take a moment before signing, compare the actual numbers on offer, whether you’re checking directly with a bank or browsing options through a platform like Finkeda Prime App, and pick the one that leaves you in a better spot a year from now, not just next month.
A business loan is meant strictly for business use, like stock, equipment, or expansion, while a personal loan can be used for any personal expense without the lender tracking where it goes.
Yes, it is feasible, but be prepared for trade-offs such as a request for a strong co-applicant, a smaller approved amount, or a higher interest rate. Remember that specific lender policies and your overall eligibility will determine the terms.
It can keep personal assets a bit more protected, offer tax relief on interest paid, and allow for higher loan amounts, especially when secured.
Mainly because it keeps personal and business finances separated and comes with tax advantages that personal loans usually don’t offer.
Personal loan eligibility generally depends on age, steady income, and credit score, while business loan eligibility depends on business vintage, financial documentation, and the credit profile of both the business and its promoters.
Secured business loans usually allow longer repayment tenures, sometimes stretching several years, while personal loans typically cap out at a shorter, fixed number of years.
Disclaimer: This article is for general informational purposes only and should not be considered financial, tax, or investment advice. Interest rates, loan amounts, eligibility criteria, repayment tenures, fees, tax treatment, and approval conditions may vary depending on the lender, applicant profile, and applicable policies. Loan approval and terms are subject to the respective lender’s assessment and terms and conditions. Please verify the latest details with the relevant lender or Finkeda before making a borrowing decision.
Share :
Like:
0