
Oct. 05, 2026

11 Min read

Investments

Share :


Parents begin to dream as soon as their child is born. They dream of their child going to a good school, doing well on tests, getting into a good college, starting a career, and then getting married with lots of family and friends. These are lovely dreams, but they can’t pay for college or a wedding on their own to achieve these dreams, you need a good money plan.
The cost of weddings and schools is going up much faster than most people think it will. This is a problem for many Indian parents. Prices keep going up, so an amount that seems big now might seem small in fifteen or twenty years. Your savings might not grow fast enough to keep up with these rising costs if you only put them in a bank account or in gold jewellery.
In this case, parents need a clear, step-by-step plan. This article will talk about how much it really costs to raise and educate a child in India today. It will also tell you about two fathers who chose different paths, provide you information on different investment options, and show you how to plan your family’s future. We’ll also show how Finkeda can help you make this happen with a plan tailored to your goals and income.
Every parent wants to give their child the best life possible. That means good school, good college and, hopefully, one day, a beautiful wedding. But all of these dreams cost money, and the cost rises every single year. In this blog we will explain in very simple words how you can plan and save for your child’s education and marriage. We will talk about why starting early is important, what savings options are available, how much money you might need and how Finkeda can help you make a plan suitable for your family.
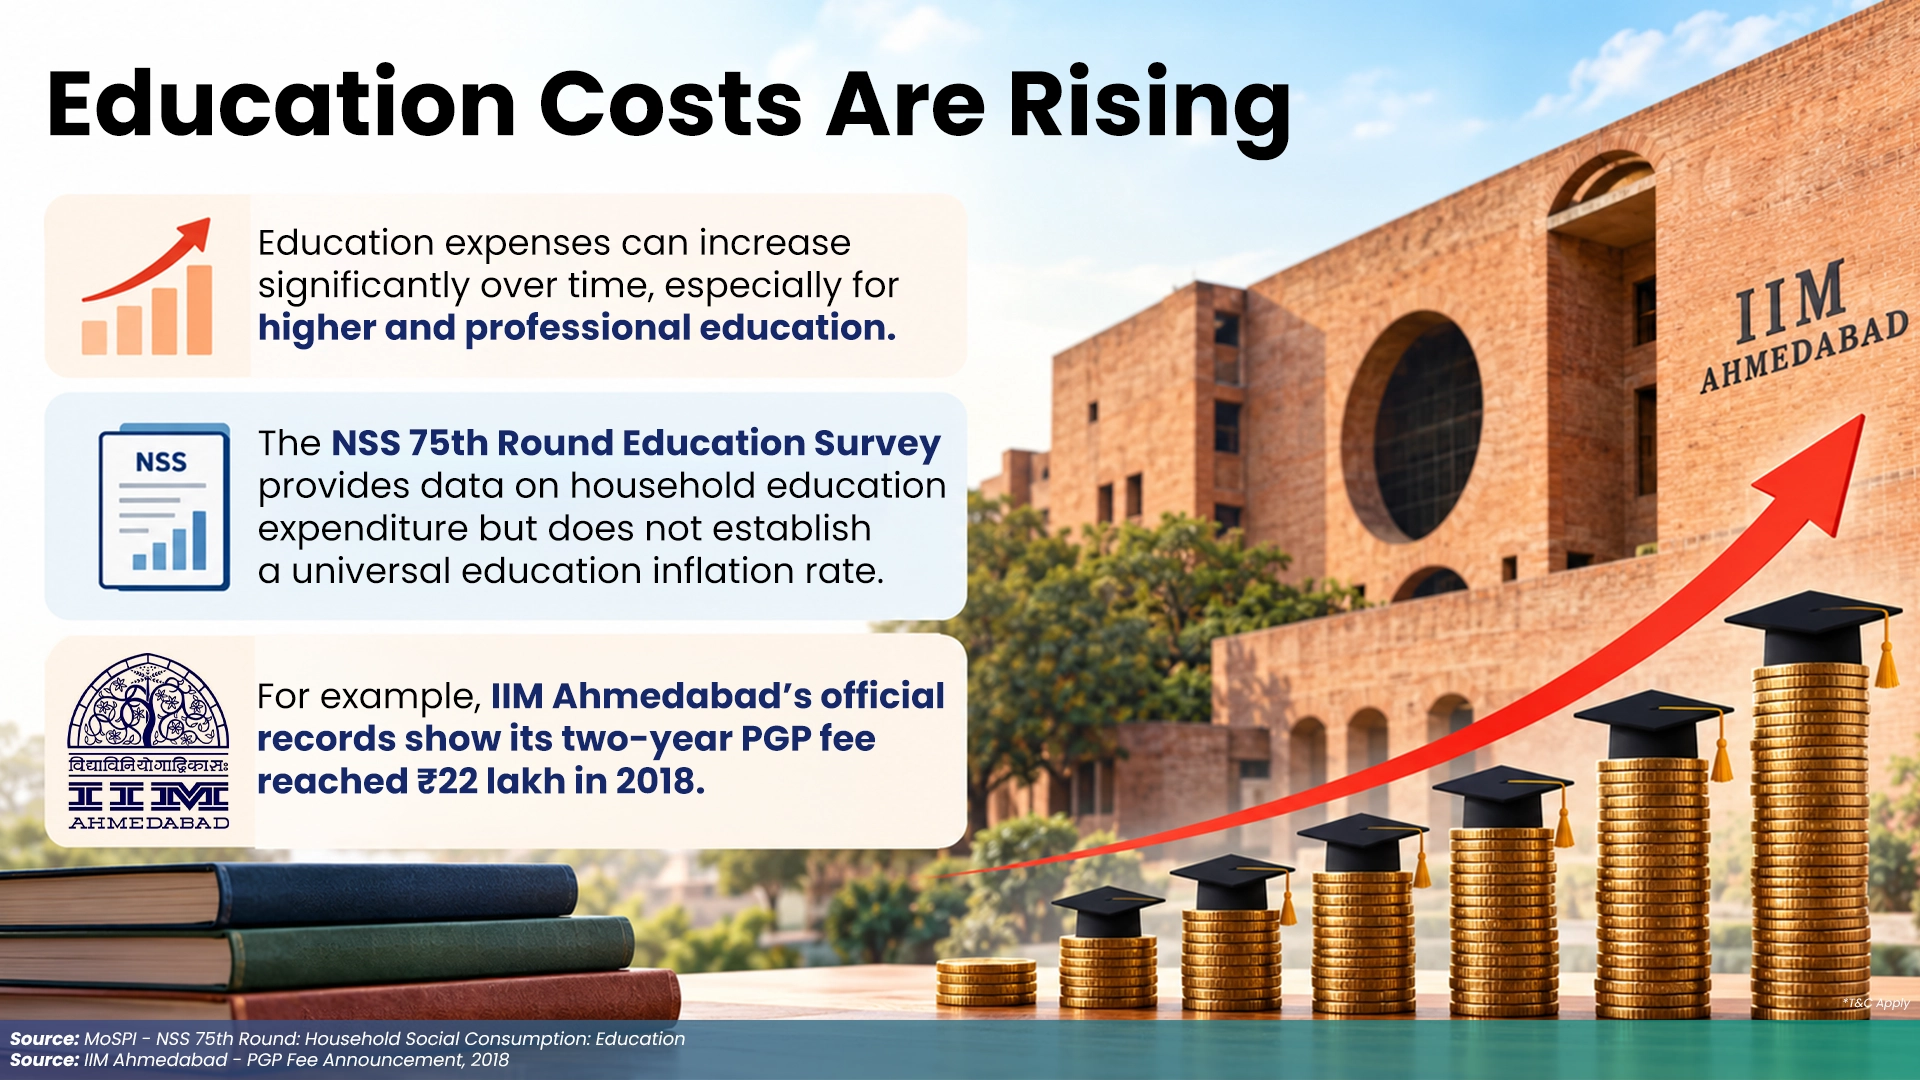
To make good plans you need to understand two simple ideas: what things cost today and what they might cost tomorrow. The difference between the two is inflation.In the education sector, escalating current costs suggest that future expenditures will be significantly higher.
On average, education costs in India increase by about ten to twelve per cent each year. That is nearly twice the rate at which normal household prices increase. That’s the same degree, but it gets more expensive every year just because time has gone by without you doing anything wrong.
Here is an example with actual numbers.
A wedding is not only an emotional event; it is also a major financial event for most Indian families. Between the venue, catering, clothes, jewellery, travel, and guest arrangements, the total bill can be very high. A wedding that would cost around twenty-five lakh rupees today could easily cost more than sixty lakh rupees in fifteen years, even if we assume a modest yearly rise of six to seven per cent.
Reading dry statistics might put you off, so let’s take a look at a short story to illustrate the significance of getting a head start. The friends Rajesh and Vikram welcomed their first children that same year. Both earned a similar salary, and both wanted to build an education fund of fifty lakh rupees by the time their child turned eighteen.
Rajesh didn’t wait. As soon as his daughter turned 1 year old, he started a monthly investment plan specifically for her education.
Vikram had every intention of saving as well, but he kept telling himself there was still plenty of time. When his son turned 10, he finally began investing.
Both fathers reached for the same goal. But look more closely at how they arrived. Rajesh invested only half as much as Vikram did, simply because he gave his money more time to grow. Vikram had to squeeze much larger amounts out of his monthly budget in a much shorter window, which is far more stressful and much harder to manage. This is the true power of starting early. Time does much of the work for you, so your monthly workload is light.
Note: Rajesh and Vikram are used here only as illustrative examples to explain a concept in simple terms. They are not real individuals, and the figures mentioned are approximate, meant purely for easy understanding rather than a guarantee of the returns or outcomes any specific person will achieve.
There is no single perfect product that covers everything. A smart parent usually builds a mix of different options, some for growth and some for safety. Think of it like building a team where different players have different strengths.
| Child Investment Portfolio | |
| Growth Options (Equity) | Safety Options (Debt & Government-Backed) |
| 1. Equity Mutual Funds (SIP) | 1. Sukanya Samriddhi Yojana (For a Girl Child) |
| 2. Flexi Cap Funds | 2. Public Provident Fund (PPF) |
| 3. Large Cap Funds | 3. Target Maturity Debt Funds |
| 4. Child ULIPs with Premium Waiver | 4. Gold Bonds |
For long-term goals of seven to fifteen years or more, equity mutual funds are usually considered to be one of the best tools available for child education planning. With an SIP, you invest a fixed amount every month, instead of a significant amount at one go. This is easier on your monthly budget and also helps average out market ups and downs.
If you have a daughter below the age of 10, Sukanya Samriddhi Yojana is one of the best investment options for a girl child in India.
If you have a son/daughter, PPF is a suitable option for complete safety.
Child ULIPs are insurance plans which provide the dual benefit of life insurance and market-linked investment growth. The most important feature involved here is something called Waiver of Premium. Every parent should get the concept clear.
This guarantee is the one feature that makes a Child ULIP different from a regular mutual fund. It is a safeguard for the child’s future in the worst case.
| Investment Decision | Risk Level | Average Return Range | Lock-in Period | Best Fit For |
| Equity Mutual Funds (SIP) | Moderate to High | long term 11%-14% | Low exit charge before 1 year but mostly flexible | higher education, college degree |
| Sukanya Samriddhi Scheme | Government-backed Very low | 8.0% to 8.5% subject to change quarterly | until 18 or 21 locked | Girl Child – Higher Studies & Wedding |
| PPF (Public Provident Fund) | Government-backed Very low | 7.0%-7.5%, quarterly change | 15 years, partial withdrawals permitted | Safe share of the education fund |
| Child ULIPs Premium Waiver | Medium difficulty | 9% to 12 % | MINIMUM 5 years | Guaranteed education fund even if parent not present |
| Gold ETFs or Govt Gold Bonds | Medium difficulty | Monitors price changes in gold | 8 years, but could be traded earlier on exchanges. | Wedding jewellery fund |
Put actual ages next to actual goals so the plan feels real and specific.
Your money mix isn’t something to stick with forever. It should move as the goal approaches.
“Your savings plan is only as strong as the income behind it. First, ensure that the main breadwinner in the family has adequate protection.
One very common and very emotional mistake many parents make is to dip into their own retirement savings or take large loans just to fund an expensive wedding or expensive course. It might feel like the right thing to do at the time but can leave you financially exposed later in life.
Remember this simple truth. Your child can opt for education loans, scholarships, etc. to fund their studies. But there is no loan on offer anywhere for your retirement.
There is a simple rule that can help you keep both goals safe simultaneously.
More habits to form.
Reading about investment options is a sensible first step, but every family’s situation is different. Your income, your existing savings, your child’s age, and your comfort with risk all play a part in deciding the right plan for you. This is exactly where Finkeda comes in.
If you want a proper, personalised plan for your child’s education and marriage goals, you don’t have to do it all alone. You can reach us in two simple ways.
Call us, connect directly with our certified financial advisors, or email us and send your requirements and questions.
Once you reach out, our team at Finkeda will take a close look at your family’s future milestones, work out the actual inflation-adjusted amounts you will need, and guide you through the entire onboarding process from start to finish.
The best time to start is as early as possible, ideally right after your child is born. This gives you a period of fifteen to eighteen years, allowing compounding to work in your favour. Starting early also means you can afford to take slightly more risk with equity investments in the early years, which usually leads to stronger long-term growth.
There is no single magic product. The smartest approach is to build a mix of different options rather than relying on just one. A combination of SIPs in diversified equity mutual funds, along with Sukanya Samriddhi Yojana for a girl child or Public Provident Fund for a boy child, usually gives you a healthy balance between strong growth potential and complete capital safety.
Keep each goal in its own separate account so you never mix up the money. Automate your retirement contributions and your child’s education contributions on the very same day your salary is credited, so both goals move forward together. Try never to withdraw from your retirement fund or provident fund for milestone expenses. If you ever face a shortfall, look first at scholarships or education loans rather than putting your own retirement years at risk.
Yes, absolutely. SIPs in equity mutual funds are one of the most effective tools for this exact purpose. Because you invest a fixed amount regularly instead of a lump sum, you naturally buy more units when prices are low and fewer units when prices are high, which smooths out market volatility over time. As your child gets closer to college age, you can gradually shift these equity units into safer debt funds, locking in the growth you have already earned before you actually need the money.
Disclaimer: Mutual fund investments and other market-linked financial instruments are subject to market risks. Please read all scheme-related documents, policy terms, and conditions carefully before investing. Past performance is not a guarantee of future returns. The numbers, examples, and asset allocation ideas shared in this article are meant purely for general information and learning purposes and should not be treated as personal tax, legal, or investment advice. Please speak with a certified financial advisor before making any final investment decisions.
This blog is intended solely for educational and informational purposes. Content reflects data at time of publication and may not accurately reflect current premiums, terms, or regulations. Readers are encouraged to confirm the accuracy and relevance of the data before making any significant decisions.
Share :
Like:
0