
Sep. 18, 2026

7 Min read

Payments

Share :


Rent day often arrives before payday, and if you’ve ever checked your bank balance a few days before the first of every month and wondered how you’d make it work, you’re not alone. Thanks to intuitive digital platforms like Finkeda Securing comprehensive coverage is now seamless thanks to a handful of digital platforms, such as Finkeda, have made it effortless to obtain comprehensive coverage. It was established for this purpose; as a result, it is now possible to pay your landlord with a credit card or rent in all regions of India.
That said, the process is not quite the same experience as swiping your card at a grocery store or a mall. Most landlords simply do not have any setup in place to accept a card payment directly, so the entire process ends up running through a third-party app that sits in the middle, converts your card charge into a bank transfer, and sends that money on to your landlord. Before you turn this into a monthly routine, it is worth taking a moment to understand exactly what happens behind the scenes and what it could end up costing you.
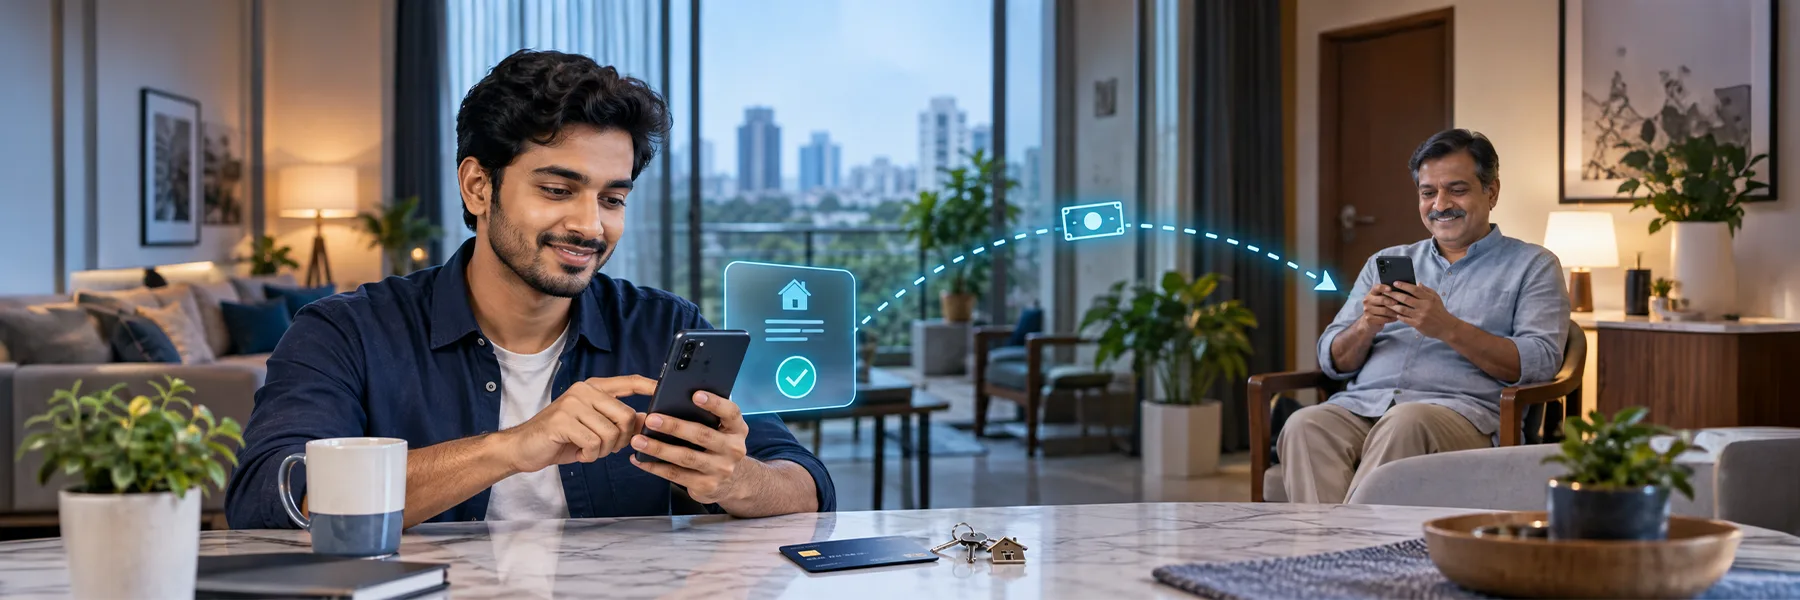
The rent payment app acts like a bridge between three parties: the payment apps as a bridge connecting three parties, you, your credit card issuer, and your landlord’s bank account. Instead of your rent leaving your savings account directly, it gets charged to your credit card’s available limit through the app, which then quietly handles the actual transfer on your behalf.
Here is what that process typically looks like, step by step, using an app like Finkeda Prime as your rent payment platform.
Step 1: Open the Finkeda Prime app. Open the Finkeda Prime app and navigate to the rent payment section, built to ensure a hassle-free payment experience.
Step 2: Enter Landlord Details Input your landlord’s banking information, including their full name, account number, and IFSC code.
Step 3: Charge the Credit Card The app charges the rent amount along with a nominal service fee directly to your credit card.
Step 4: Instant Cash Transfer Once the payment is approved, the Finkeda Prime app routes the funds directly to your landlord’s bank account using secure NEFT or IMPS networks.
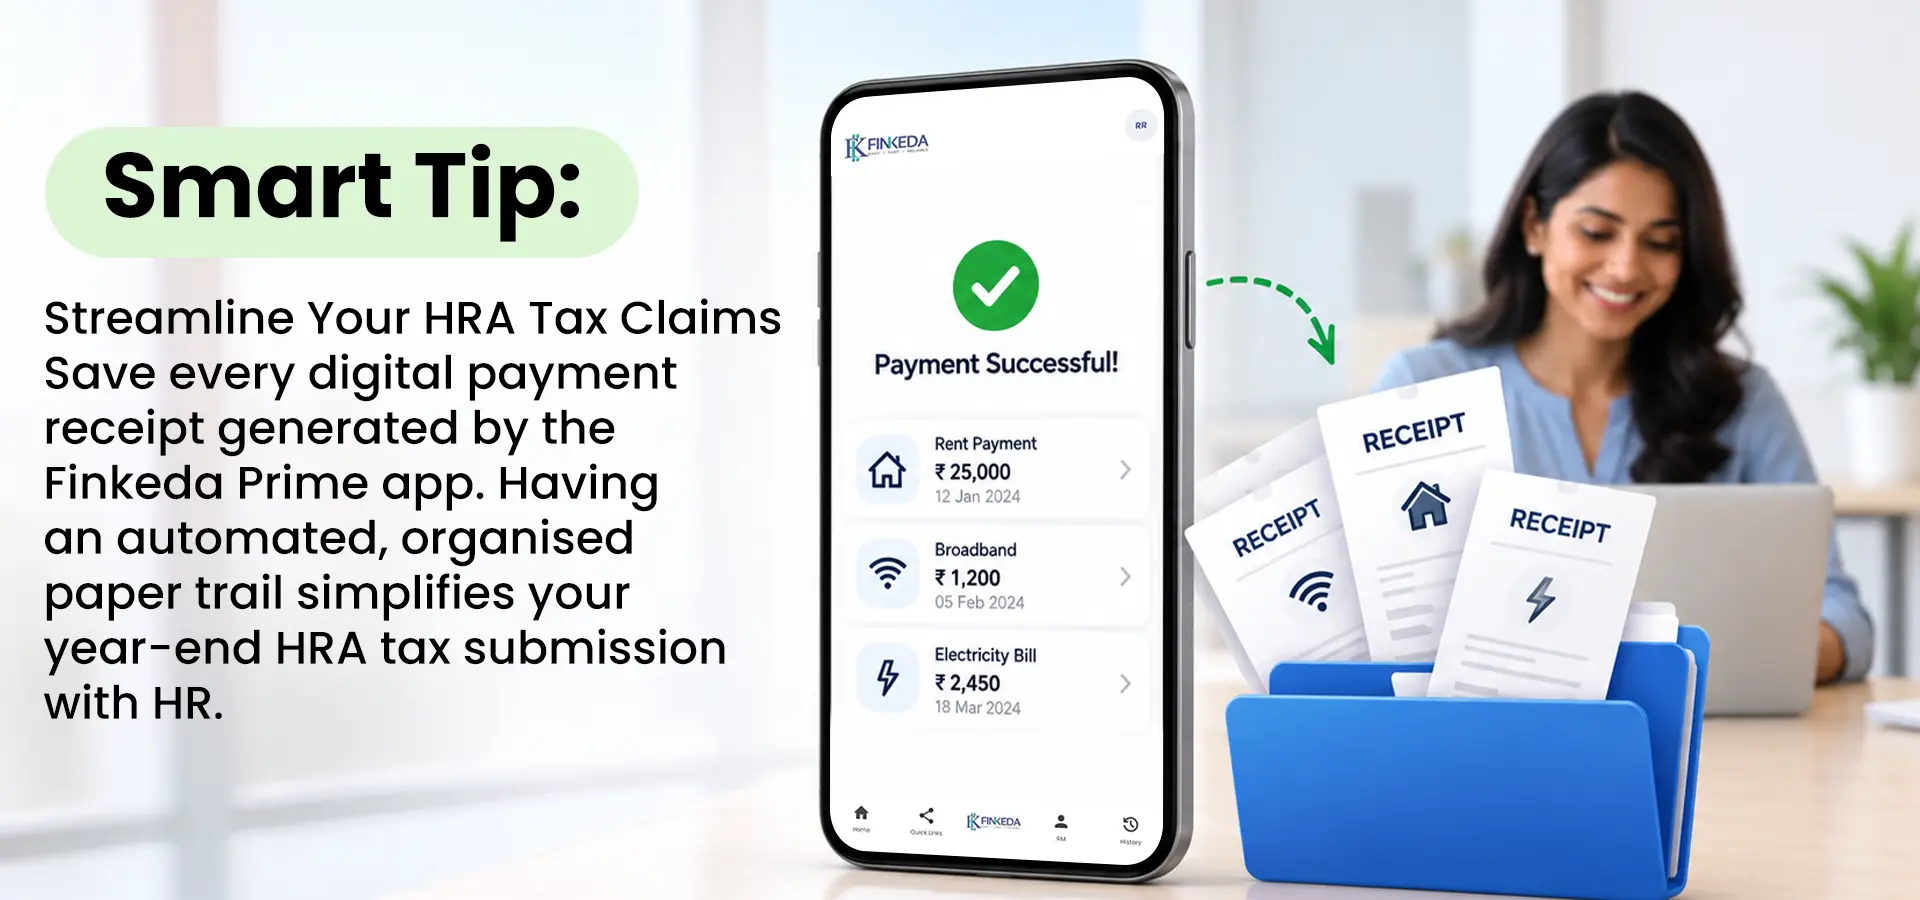
Step 5: Get Instant Digital Receipt Receive an instant digital confirmation receipt on your phone, perfect for your personal records or HRA tax claims.
Additionally, if you use your credit card prudently, there are a few very real ways you can benefit from putting your rent on it.
One of the most appealing aspects for the majority of individuals is the breathing space that it offers. In the event that you are required to make a rent payment on the first of the month, but your salary typically arrives a week later, the interest-free period of your credit card can allow you to comfortably cover the gap. This eliminates the need to borrow money from your savings or have an awkward conversation with your landlord about a late payment.
Additionally, it can assist you in reaching spending milestones that you might have missed otherwise. Even if a credit card does not award points for paying when you rent directly, the sheer magnitude of the rent transaction can cause your total spending to exceed annual thresholds.
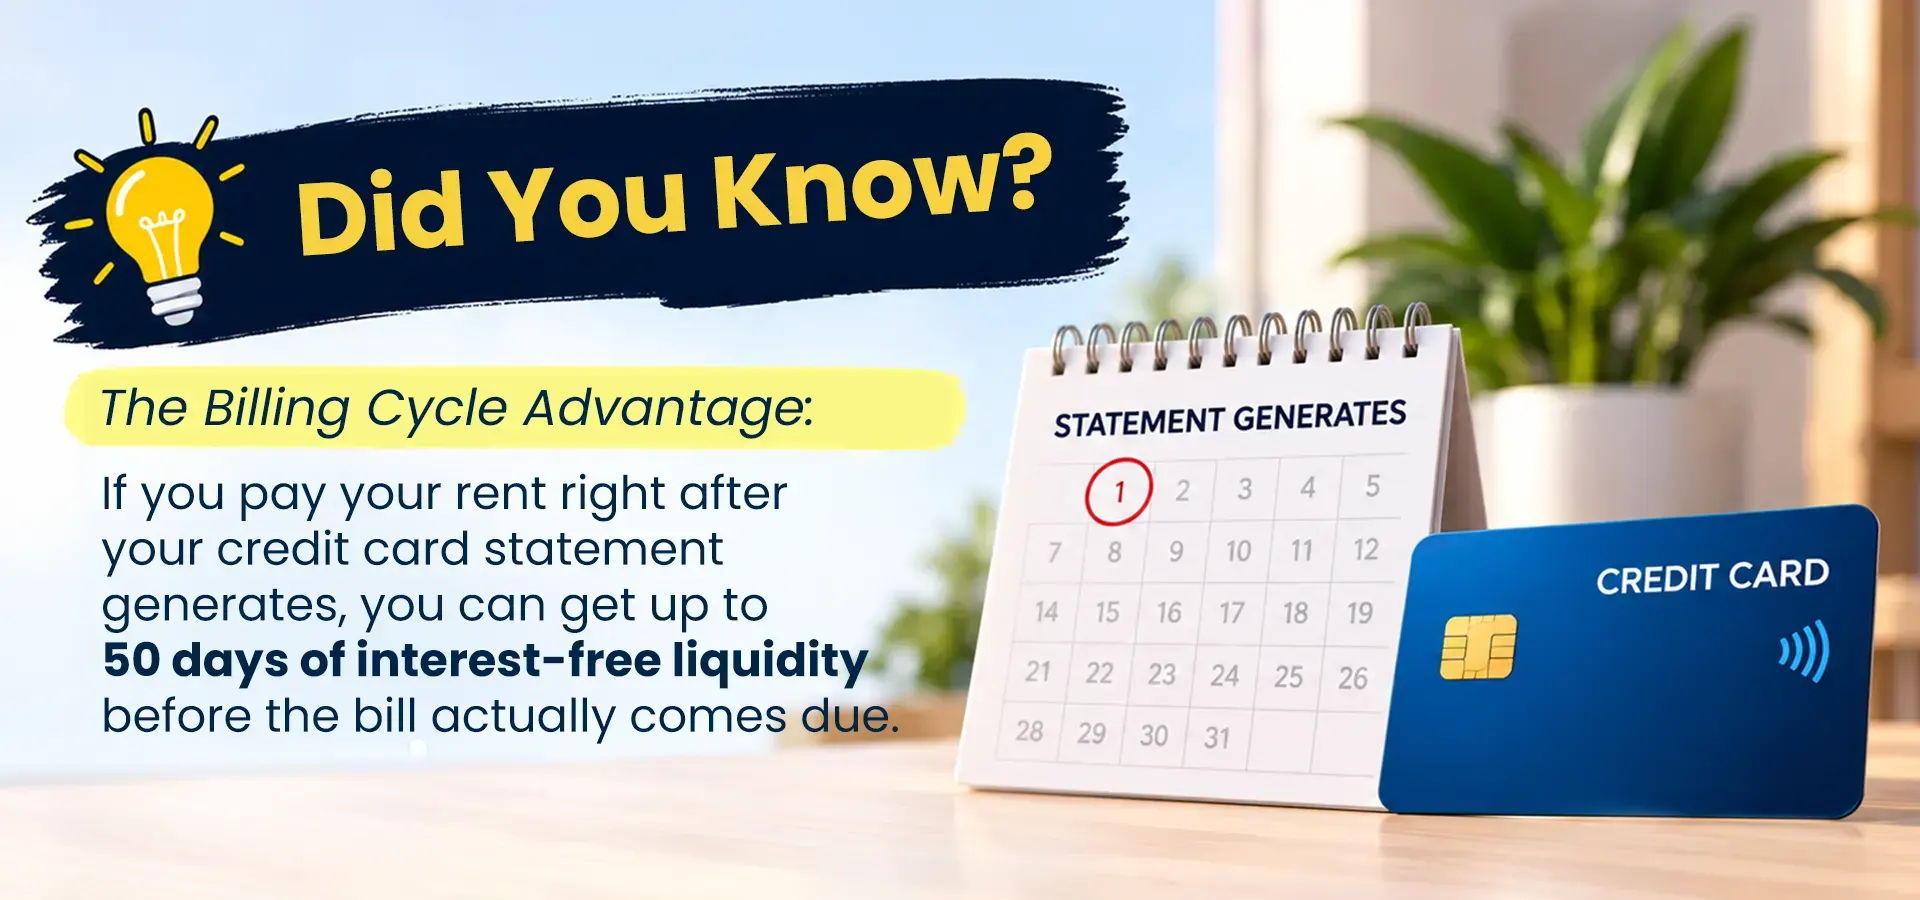
Beyond that, it can also quietly build up your credit history over time. Rent is large, stable, and easy to foresee. It’s a true way to build a history of on-time payments, as long as you are paying your statement in full every month.
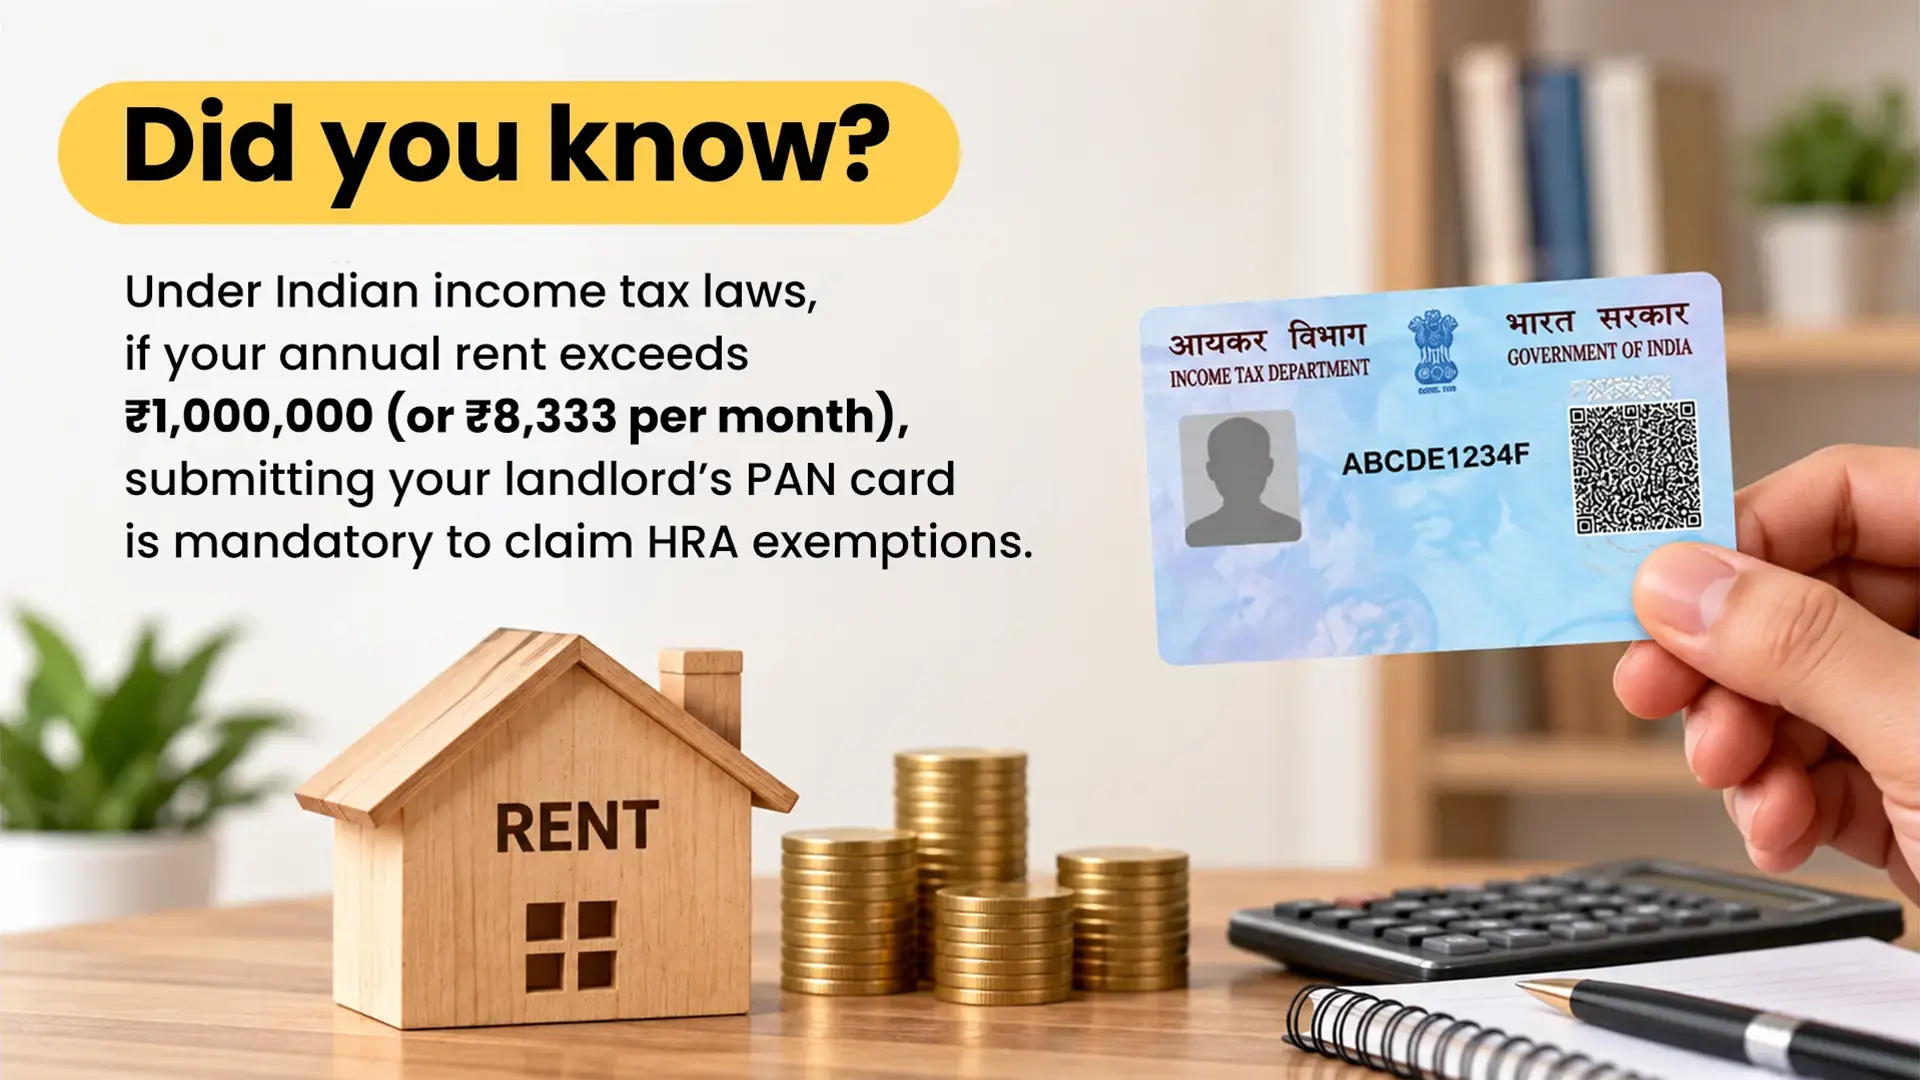
It also usually simplifies your paperwork a lot. Every time you pay through these apps, a digital receipt gets automatically generated, which makes it much simpler to claim HRA exemptions at tax time without a last-minute rush.
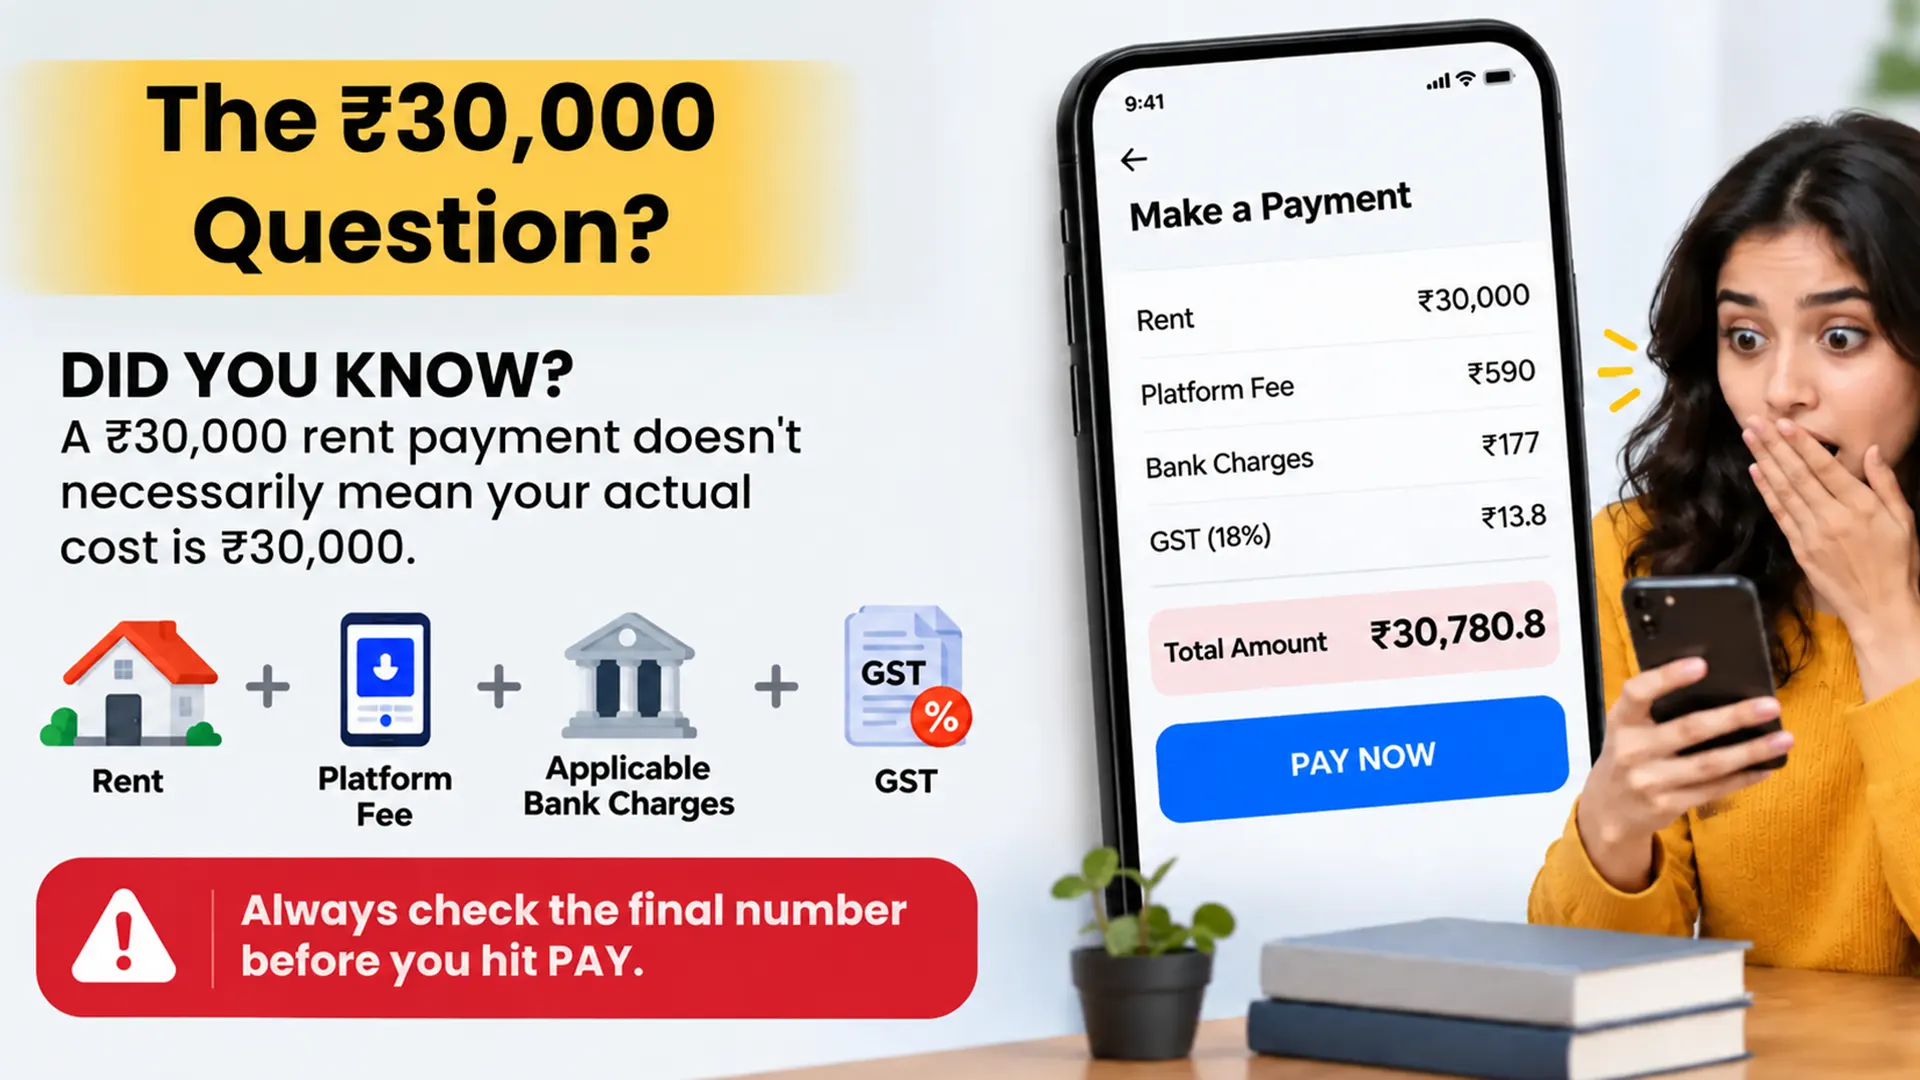
Digital payment platforms charge a nominal convenience fee on transactions, which is calculated as a percentage of the total payment amount.
When a transaction is flagged under a rental merchant code, several major banks in India now apply their own separate charge, which is typically somewhere around one percent + GST. This fee is in addition to the fact that the GST is already applied. Therefore, in actuality, you might end up paying twice: once to the app and then again to your bank.
It is also important to be aware of the risk associated with cash advances. It is possible that certain card issuers will consider certain rent payment transactions to be cash withdrawals rather than regular purchases. If this occurs, you will not have a grace period and will be charged interest immediately. Before you begin to rely on this method on a regular basis, it is important to check with your bank because interest and additional fees begin to accrue simultaneously the moment you begin using it.
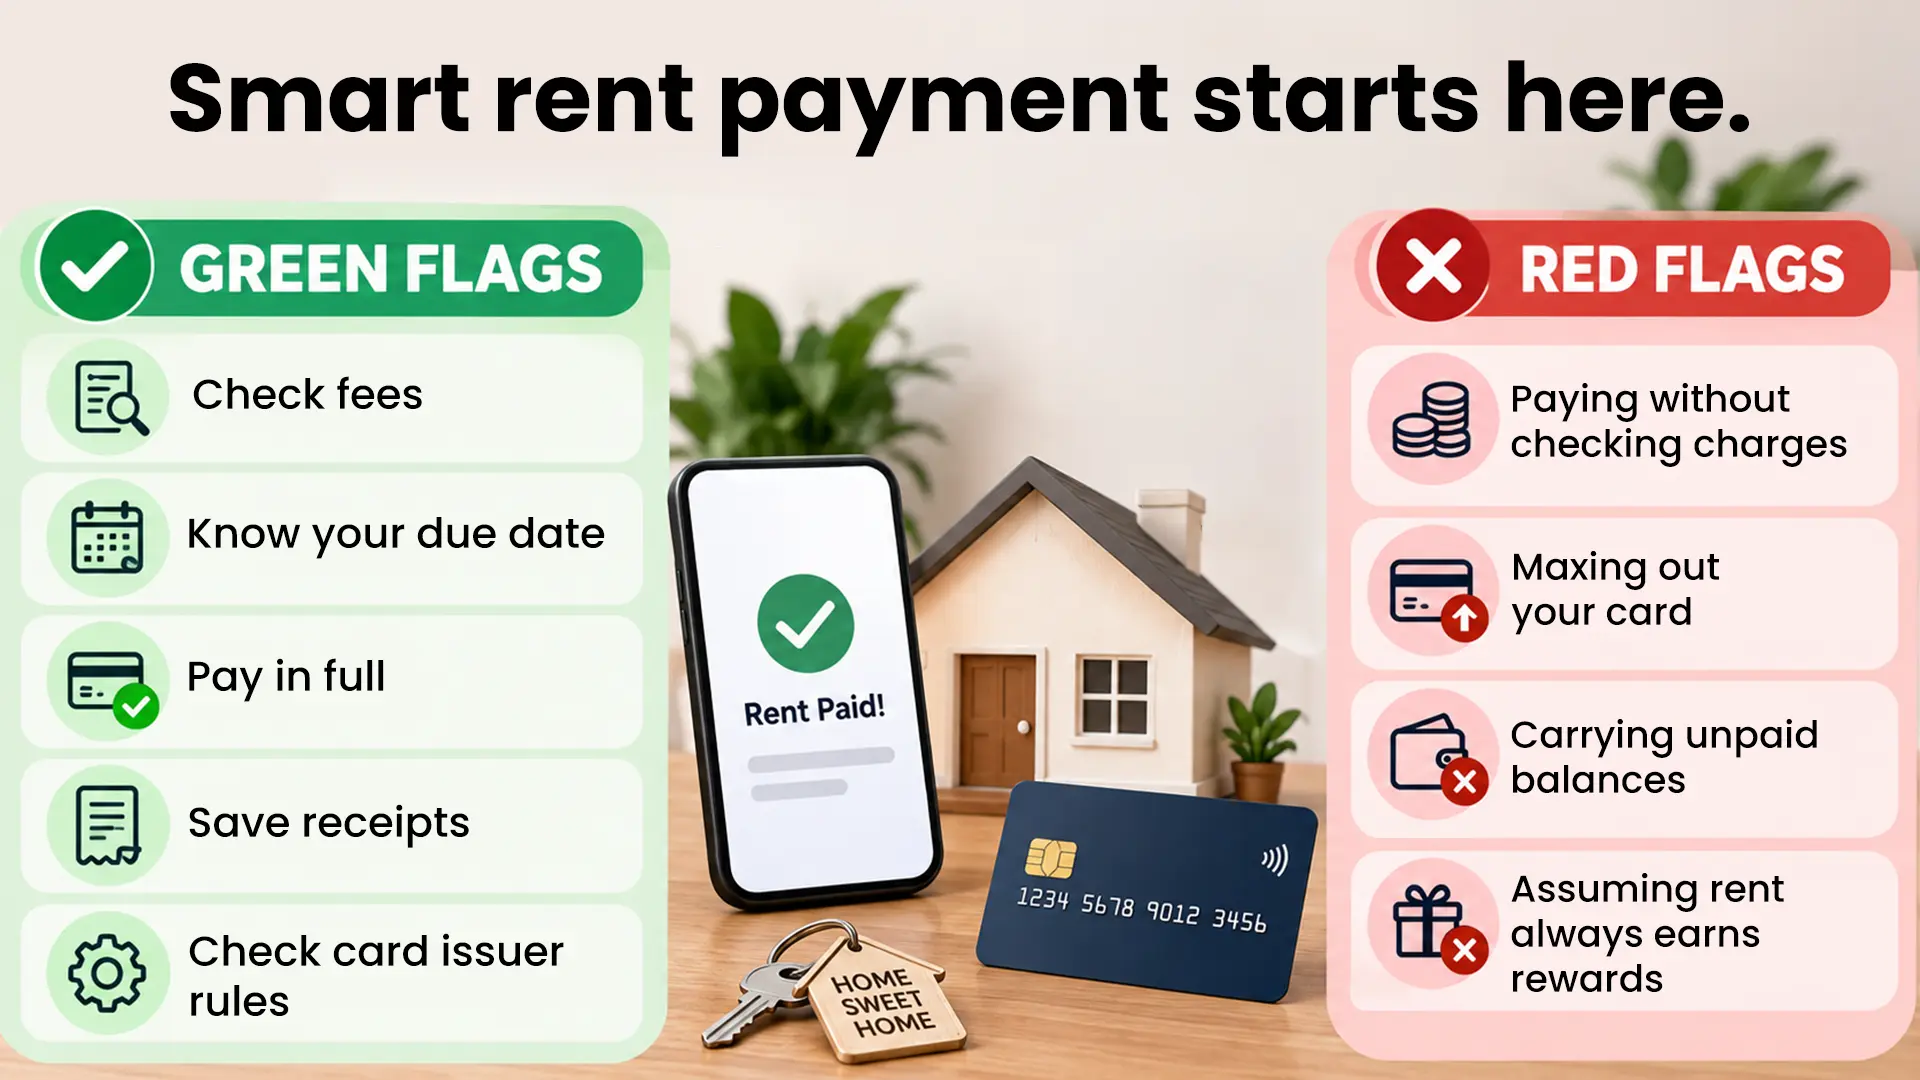
It is important to note that if you do not pay off your balance in full, you will be subject to revolving interest rates, which typically range from thirty-six to forty-five per cent on an annual basis in India. Just one month with an unpaid balance can make it impossible to earn the perks you were expecting.
The ability to navigate rental category transactions requires striking a balance between convenience and awareness of fees. Finkeda emphasises that users can optimise their monthly cash flow, build credit discipline, and make informed payment choices safely if they follow these core principles closely.
Whether you should use a credit card to pay rent is a personal decision that should be based on your financial situation and your ability to be financially responsible. More important than points or cash back is the ability to pay on time, regardless of when payday is, while keeping a clean, automatic paper trail ready for tax season for many renters.
The catch is that there have been numerous changes to the fee structure throughout the years. While some platforms did provide substantial cashback in the beginning, the majority of rent transactions now do not earn any rewards at all, and banks have become much more aggressive in adding surcharges. To get the best results, pay off your statement in full every month, research your bank’s policy on rent transactions, and look for a platform with competitive fees.
When it comes to all of these transactions, security is as important as cost. Always verify the amount displayed on screen before approving any OTP, only use platforms that are well-established and appropriately regulated, and don’t share your CVV with anyone. If you exercise caution, this tool can become a valuable asset instead of an expensive habit.
Yes, it is a widely used option today, made possible through third-party apps that charge your card and transfer the funds directly into your landlord’s bank account on your behalf.
Mainly cash flow management. It lets you pay rent on time by using your card’s interest-free period, even when your salary happens to come in a few days late.
Compare the total fees against the benefits you would actually earn from the transaction. Only go ahead if the value genuinely works out in your favour; otherwise, a fee-free option like UPI is the better choice.
Generally yes, provided you use a trustworthy platform like the Finkeda Prime app. Not every rent payment app is directly regulated by the RBI itself; many platforms operate as technology facilitators that route payments through RBI-licensed partner banks and payment aggregators. It is always recommended to verify a platform’s authorised payment partners before using it regularly.
It really does vary by bank and card. Many issuers exclude rent from reward-earning categories altogether, though some still allow it. Either way, rent payments typically still count toward the spending needed to waive your annual fee, so it is worth checking your specific card’s terms to be certain.
Disclaimer: This article is for general informational purposes only and should not be considered financial or tax advice. Credit card fees, rental transaction charges, rewards, interest rates, eligibility, and payment terms may vary by card issuer and service provider. Please verify the applicable charges and terms with your bank or payment provider before making a payment.
Share :
Like:
0