
Oct. 23, 2026

9 Min read

Payments

Share :


A credit card can make everyday payments easier, provide access to short-term credit, and offer benefits such as rewards, cashback, discounts and EMI options. But using a credit card is different from spending money from your bank account.
When you use a credit card to make a purchase, the amount is generally added to your outstanding balance and must be repaid according to the card’s billing cycle and payment terms
For a first-time user, terms such as credit limit, billing cycle, statement date, total amount due, minimum amount due, interest-free period and credit utilisation can seem confusing. Understanding these basics can help you use a credit card responsibly and avoid unnecessary interest or charges.
This guide explains how credit cards work in India, how billing and repayment work, how credit cards can influence your CIBIL score, and what beginners should know before using one.
A credit card allows you to make purchases using a pre-approved credit limit provided by a card issuer. Instead of immediately deducting money from your savings account, the issuer pays the merchant, and you repay the amount later.
Every month, your transactions are consolidated into a credit card statement. The statement generally shows your total amount due, minimum amount due, payment due date and details of individual transactions.
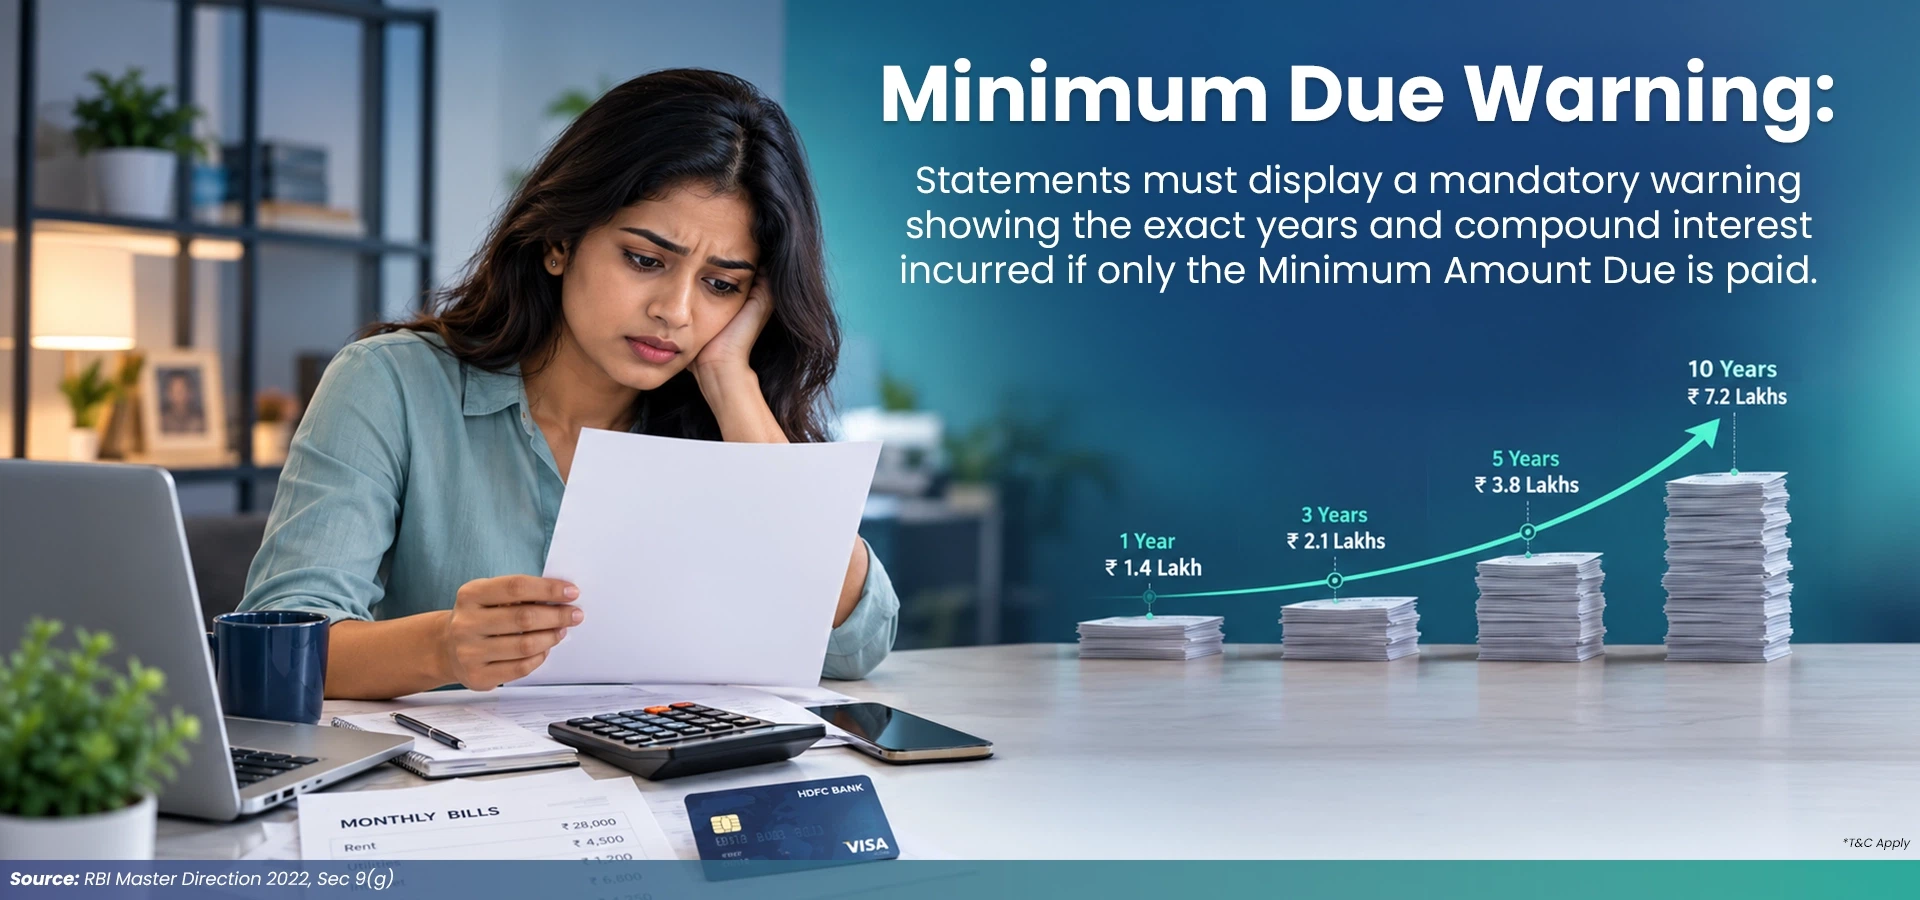
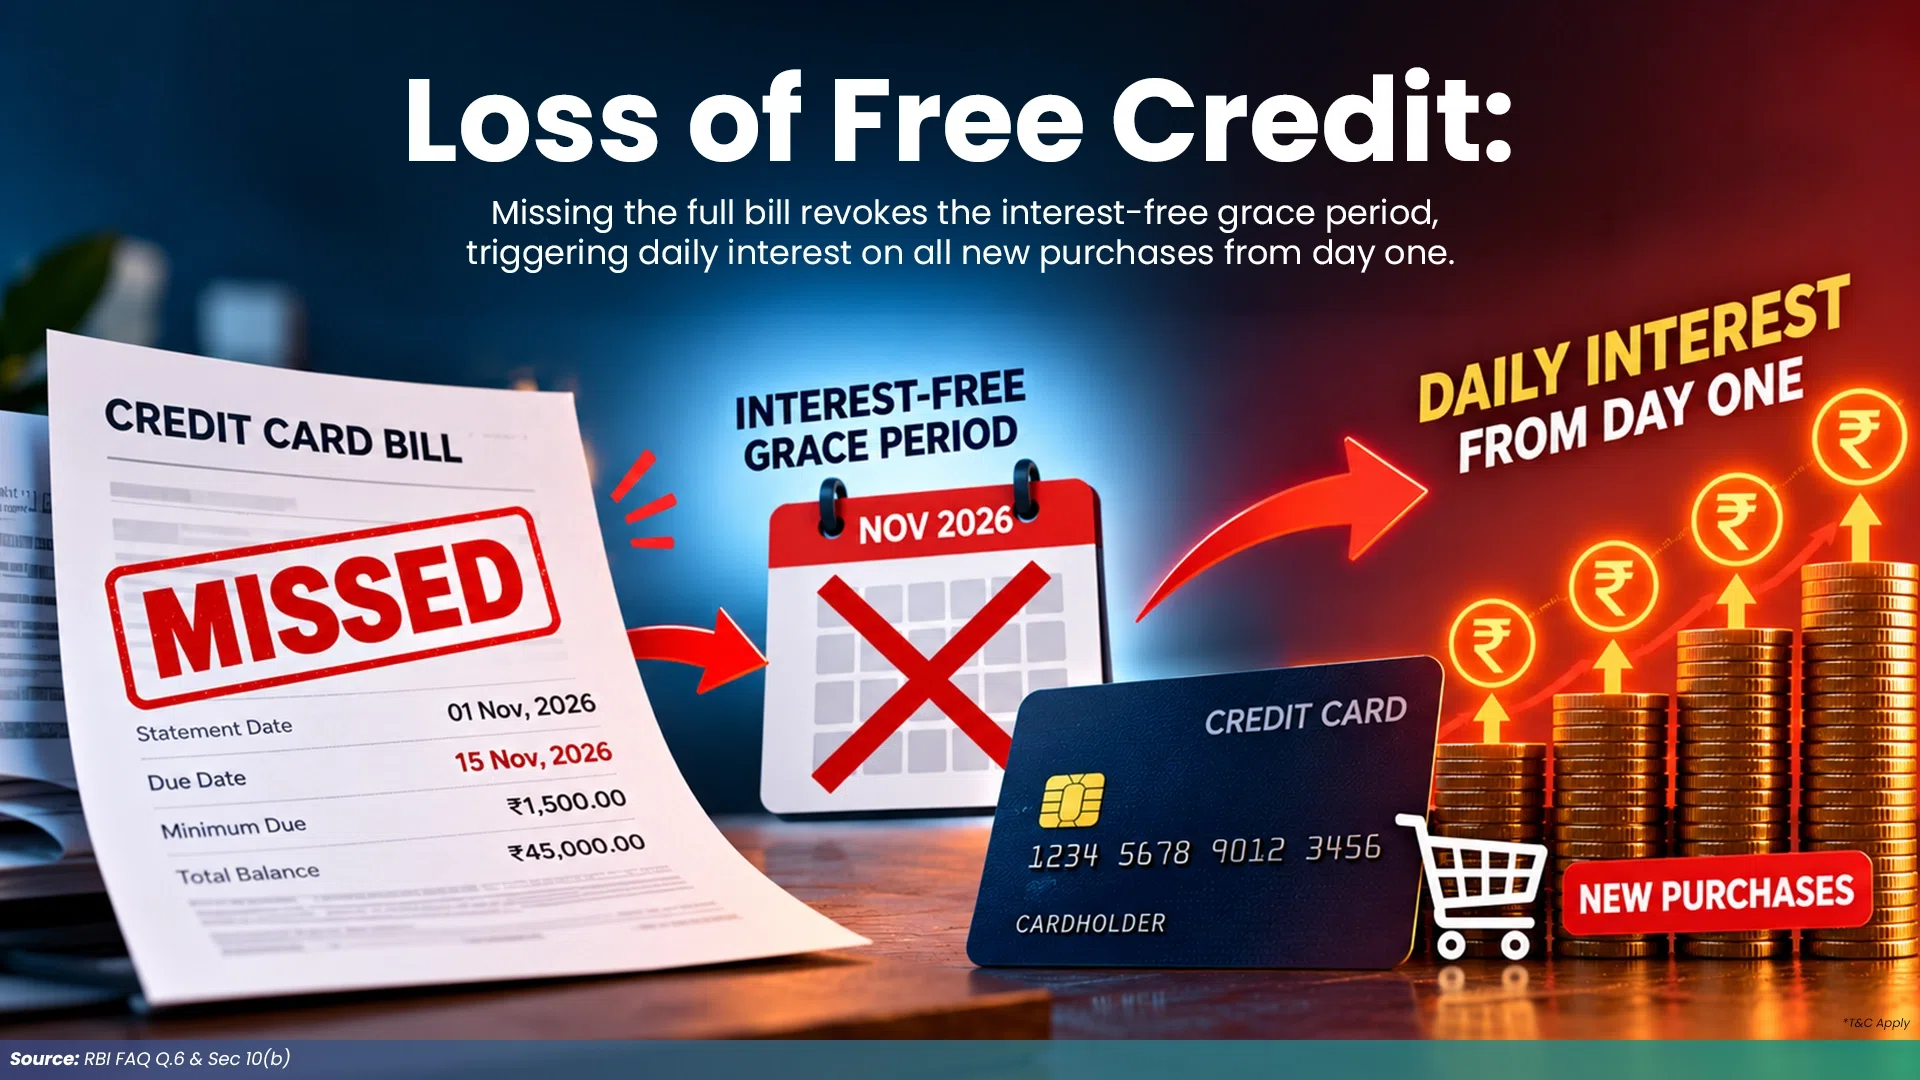
Paying the total amount due by the due date is generally the simplest way to avoid interest on eligible purchases. Paying only the minimum amount due can keep the account from becoming overdue, but the remaining balance can attract interest and may make repayment considerably pricier. RBI guidance also highlights that when the total amount due is not cleared by the due date, the interest-free credit period can be lost.
Responsible credit card use can also contribute to a healthy credit profile. Payment history and credit utilisation are among the factors that CIBIL considers when calculating your score.
Source: Reserve Bank of India (RBI), Frequently Asked Questions on Credit Card and Debit Card, Question 6
A credit card is a payment method that allows you to make purchases using a pre-approved line of credit. When you use a credit card, the amount spent is generally added to your outstanding balance rather than being immediately deducted from your bank account. You then repay the issuer according to the card’s billing cycle and payment terms.
For example, your credit card has a limit of Rs. 50,000. Suppose if you buy a laptop worth Rs 20,000, your available credit will reduce to Rs 30,000. Then you will have to pay the balance due as per your bill.
Disclaimer: This example is just for demonstration purposes. Actual credit limits, available balances, payment amounts, interest rates and fees will vary based on the terms of the card issuer and how the individual account is used.
A credit card is not extra monthly income. It offers a revolving line of credit that needs to be repaid in a timely manner. CIBIL defines a credit card as a facility that is extended to the cardholder for making purchases up to a pre-agreed limit. The statement reflects all the purchases made in a particular month, and it needs to be paid on time.
Note: Billing cycles and statement dates can vary by card issuer and card type. Please refer to your card statement or issuer’s terms for the exact billing period.
A credit card’s billing cycle is the fixed timeframe during which transactions are tracked and compiled into a monthly statement.
| Term | Importance | What it Means |
| Billing cycle | The number of days between statement generation dates (typically 28 to 31 days). | Decides exactly which purchases will appear on a particular invoice. |
| Date of Declaration | The day the statement is completed and issued. | Locks in your total balance, applicable fees and payment deadlines. |
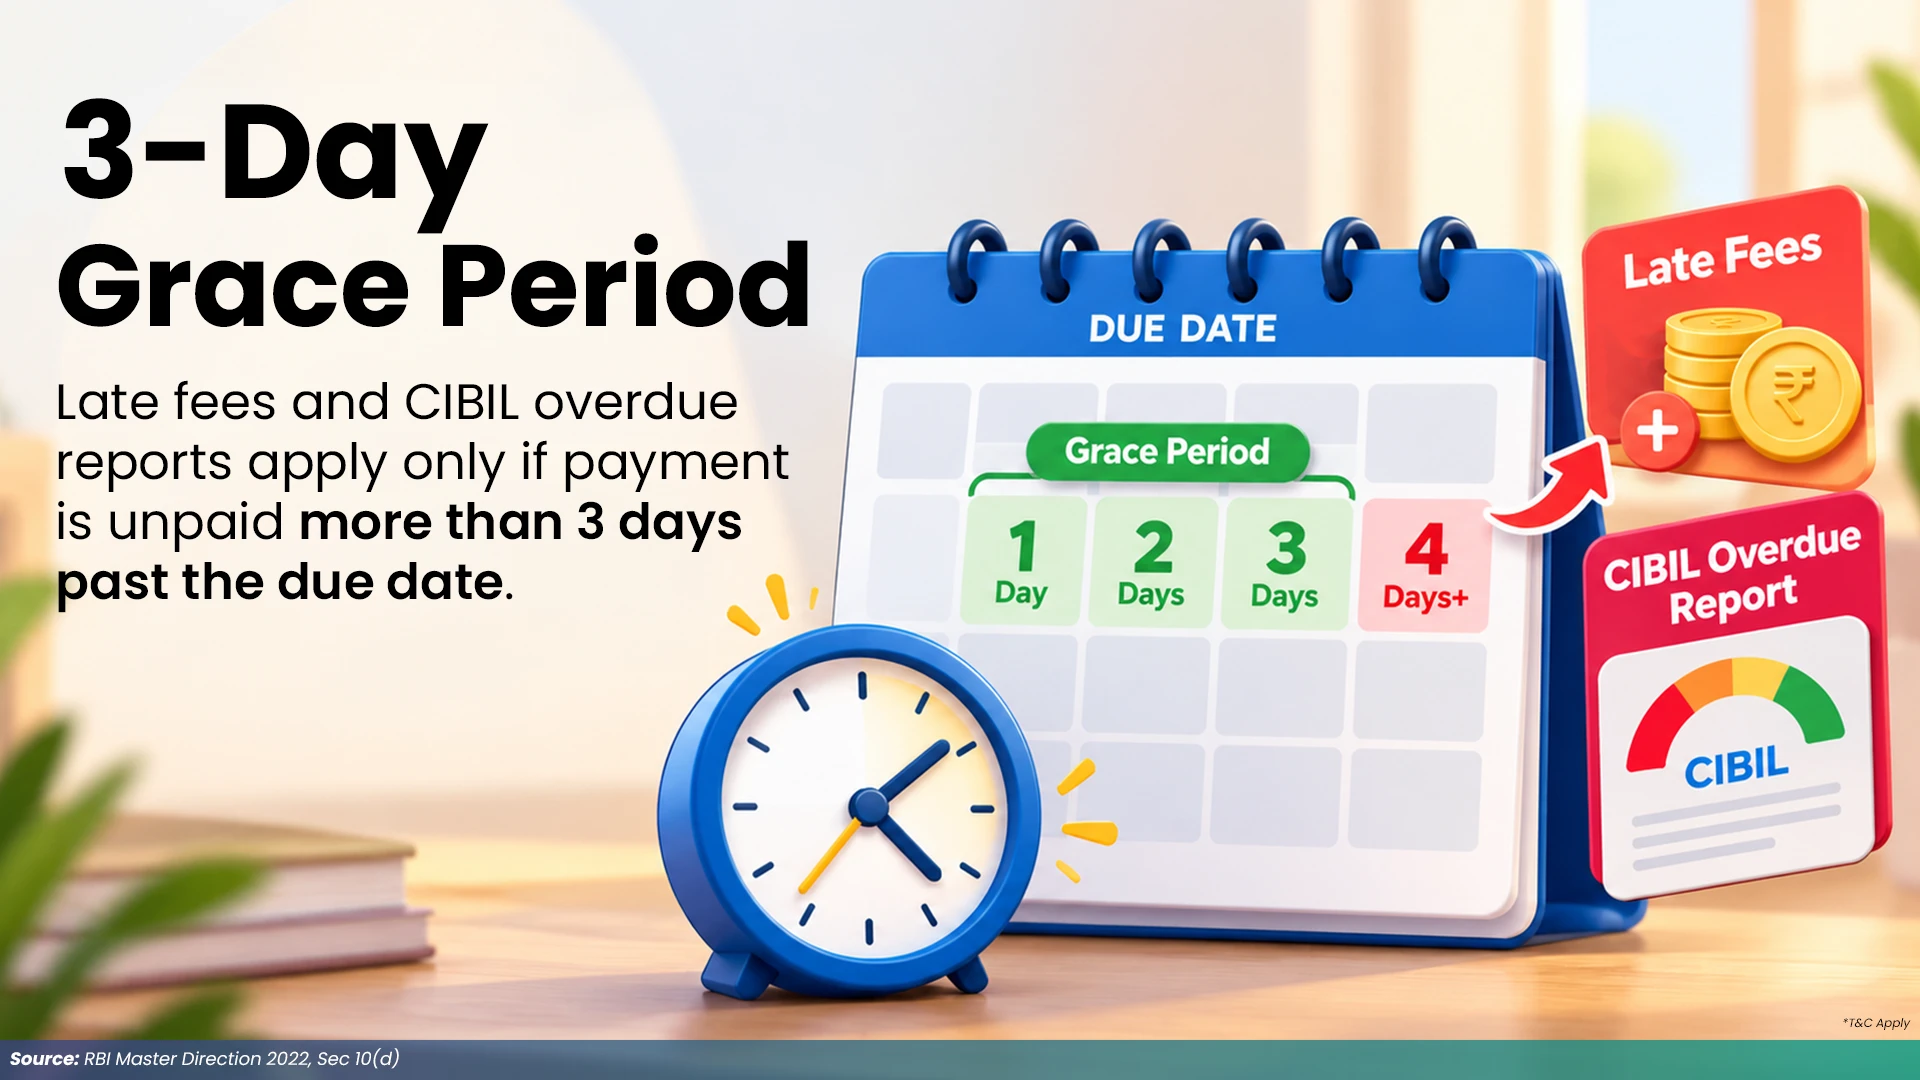
| Payment Due Date | The date by which the minimum or the full amount must be received. | If you pay by this date, you will not be subject to late fees or interest penalties. |
Note: Late fees, interest and applicable charges depend on the card issuer’s terms. Paying the total amount due by the applicable due date may help avoid interest on eligible purchases, subject to the card’s terms.
Source: Reserve Bank of India (RBI), Frequently Asked Questions on Credit Card and Debit Card.
Note: The minimum amount due is determined by the card issuer and may vary. It should not be assumed to be a fixed percentage for every credit card.
Note: Cash advance fees, interest rates and applicable charges vary by card issuer. Check the applicable Schedule of Charges before using a credit card for cash withdrawal.
| Factor | Mechanism | Score Impact | Recommended Practice |
| Payment History | Tracks timely payments versus late settlements or defaults. | High | Pay the complete statement balance on or before the due date. |
| Credit Utilisation Ratio (CUR) | Measures utilized credit against the overall limit (e.g., ₹25,000 spent out of ₹1,00,000 = 25%). | High | Maintain aggregate credit utilized strictly below 30%. |
| Credit Enquiries | Logs hard enquiries made by financial institutions during new applications. | Moderate | Space out new credit card and loan applications across several months. |
| Average Account Age | Evaluates the lifespan and stability of active credit lines. | Moderate | Keep older, low-maintenance cards open to lengthen repayment track record. |
Note: Credit utilisation is one factor considered in credit assessment. There is no universal regulatory requirement that every consumer must keep utilisation below exactly 30%. Maintaining lower utilisation may generally be viewed positively, but scoring models and lender practices can vary.
Eligible transactions can often be converted into Equated Monthly Installments (EMIs) to spread capital expenditures over fixed durations. However, EMI plans are rarely free of costs. Before opting into an EMI plan, evaluate:
Note: EMI interest rates, processing fees, GST, tenure and foreclosure or pre-closure charges vary by issuer, transaction and offer. Check the applicable terms before converting a purchase into EMI.

Note: Card categories, features, eligibility criteria, fees and benefits vary between issuers. A card may also combine features from more than one category.
A credit card serves as a convenient payment instrument rather than supplemental income.
Mobile financial platforms make it easier to manage and track your credit and payments in one place. Platforms like The Finkeda Prime are part of this financial services ecosystem and help users explore different digital payment services. When using these platforms, check the fees, charges, terms and total cost before choosing a service, rather than focusing only on convenience.
Note: The suitability of a credit card depends on the individual’s financial situation, repayment capacity, card terms, fees and intended usage.
A credit card is neither automatically good nor bad. It is a financial tool, and its usefulness depends on how responsibly you use it.
For beginners, the most important things to understand are your credit limit, billing cycle, statement, total amount due, minimum amount due and payment due date.
If you consistently pay on time, keep your credit utilisation under control, understand applicable fees and avoid unnecessary borrowing, a credit card can become a convenient part of your financial routine.
As digital financial services continue to make payments and credit more accessible, platforms such as Finkeda can play a role in helping consumers access financial services conveniently. The smarter approach, however, is always to combine convenience with financial awareness.
Use the credit available to you responsibly, understand the costs before borrowing, and make repayment a priority.
A credit card provides a predefined credit limit that you can use for eligible purchases. The transactions are accumulated during your billing cycle and shown in your monthly statement. You then repay the amount according to the statement and payment due date.
A billing cycle is the period during which your credit card transactions are recorded before the issuer generates your statement. The statement then shows the amount payable and the applicable payment due date.
The total amount due is the amount payable for the statement according to the card’s terms. The minimum amount due is the minimum payment required by the issuer by the due date. Paying only the minimum does not clear the entire outstanding balance and can result in interest on the remaining amount.
Pay the total amount due by the payment due date, subject to the card’s applicable terms and eligibility for the interest-free period. Avoid carrying an unpaid balance unnecessarily and understand the interest and fee structure of your card.
Responsible credit card use can contribute to a healthy credit history. Payment history, credit utilisation, age of credit and credit enquiries are among the factors considered in CIBIL scoring. Late payments, high utilisation and frequent applications for new credit can negatively affect your credit profile.
Some eligible credit card purchases can be converted into EMI, depending on the card issuer and applicable terms. Before choosing EMI, check the interest rate, processing fee, tenure, taxes and total repayment amount.
Paying the minimum amount can satisfy the minimum payment requirement, but it does not clear the entire bill. The remaining balance may attract interest and the interest-free period may be affected.
It can be useful if you have a predictable income, understand the repayment terms and can pay your bills on time. A credit card should be used within your repayment capacity rather than as a way to spend beyond your means.
No. CIBIL states that checking your own CIBIL score does not impact the score.
No. Simply owning a credit card does not guarantee a higher score. Responsible payment behaviour, controlled utilisation and other aspects of your credit history matter.
Note: The answers below are general educational information. Actual interest rates, fees, billing practices, eligibility, credit limits and other terms may vary by card issuer and individual card agreement.
Final Regulatory & Compliance Disclaimer: Credit card issuance, card limits, annual fees, interest calculation methodologies, and EMI eligibility remain at the sole operational discretion of the respective card issuer or banking institution, guided by Master Directions issued by the Reserve Bank of India (RBI). Platform names serve strictly as illustrative examples of digital financial tools and do not constitute an endorsement, solicitation, or financial underwriting. Always review the Key Fact Statement (KFS) and Schedule of Charges issued with your card before completing financial transactions.
This blog is intended solely for educational and informational purposes. Content reflects data at time of publication and may not accurately reflect current premiums, terms, or regulations. Readers are encouraged to confirm the accuracy and relevance of the data before making any significant decisions.
Share :
Like:
0