
Sep. 14, 2026

7 Min read

Loan

Share :


Cash flow is a perennial worry for independent retailers, MSMEs and self-employed professionals throughout India. Growth capital is another. Waiting weeks for a bank to approve a loan can cost you a good inventory deal, a seasonal sales window, or the machinery upgrade your business actually needs right now. A credit line you can count on isn’t just nice to have. It’s what lets small business owners keep moving instead of sitting around waiting for approvals.
That’s the gap Finkeda is trying to close with its partnership with Muthoot FinCorp. Together they offer a credit facility built for self-employed professionals and shop owners, one that skips collateral and cuts through most of the usual banking delays. The idea is simple: pair decent technology with a repayment schedule that fits daily business income, and give owners the capital they need without the wait.
Core Definition: A financial tool made to bring flexible and fast capital into daily business operations and expansion plans.
Loan Parameters: Unsecured funding is available from ₹50,000 up to ₹10,00,000, with repayment tenures that range from 104 to 373 days.
Daily Repayment Model: The loan runs on an EDI (Equated Daily Installment) system, so repayments line up with the money actually coming into your business each day.
Streamlined Underwriting: The eligibility rules aren’t complicated. You need a minimum CIBIL score of 650 and at least 2 years of running your business.
Digital Application Process: The process includes digital document submission, bank statement analysis, Video KYC and Video Personal Discussion.
A lot of people ask this question, and honestly the answer isn’t complicated. A business loan is just a credit agreement between you and a lender, where the money has to go toward the business, not your personal expenses.
Think of it less as debt and more as a way to stay flexible when things get unpredictable. Instead of burning through your own savings during a slow month, you borrow to get through it, or to buy stock in bulk, or to pay a vendor before your own payments come in.
Finkeda handles this digitally, and the repayment side is where it feels different from a normal loan. There’s no single heavy EMI sitting on your account once a month. Payments get pulled in small daily amounts instead, straight from your business account, so you barely notice them.
It helps to know where the bar is set before you even start filling out the form. That way there’s no surprise later, and your credit score stays protected too.
These are the conditions checked by Muthoot FinCorp’s automated Business Rules Engine (BRE).
Age Bracket: Between 21 and 60 years old at the time of application.
Business Vintage: At least 2 years of continuous operation, no long gaps.
Debt Burden Cap: Your overall debt load has to stay within a 50% FOIR (Fixed Obligation to Income Ratio).
Target Market: Self-employed individuals.
None of this needs to be printed out or carried around. Everything on this list can be checked online, and there isn’t much of it.
Identity and Address Proof (KYC): A scanned Aadhaar card and PAN card – that’s really it for identity.
Proof of Business Operation: GST registration, a shop establishment licence, or a partnership deed that confirms 2 years in business.
Financial Performance Trails: At least 6 months of bank statements, uploaded digitally so the system’s bank statement analyser can go through them.
No more standing in bank lines, no thick paper files, no stack of post-dated cheques to sign. You can do all of these tasks from your own desk.
Download the Finkeda Prime App.
Select “Business Loan”.
Enter Your Basic Details
Upload the Required Documents
Complete the Remaining Steps
Submit Your Loan Application
How Does Credit Score Impact Business Loan Approval and Interest Rates?
Your credit history basically works as your business’s financial reputation. Lenders read it closely when they’re deciding on your business loan interest rate, since it tells them how you’ve handled past payments.
1. The Scoring Baseline: A CIBIL score of at least 650 is the entry point. New to credit borrowers aren’t automatically ruled out either, as long as they meet certain surrogate banking criteria.
2. Strict Bureau Knock-Out Rules: Lenders are cautious about risk, so a few hard rules apply. Applications get rejected if there’s an overdue balance above ₹5,000, or if the applicant has payment delays such as 30+ days past due in the last 3 months, 60+ days past due in the last 6 months, or 90+ days past due in the last 12 months.
3. Operational Stability Metrics: For smooth processing, there should be no loan settlements or write offs in the past 12 months. Try to keep credit inquiries down too, three or fewer in the last 30 days is a safe range.
Almost every growing business runs into this at some point, daily bills piling up while a client’s payment is still weeks away. A well structured business loan can take the edge off that pressure.
Traditional loans, with their large monthly EMIs, can put real strain on a small business. The EDI system spreads repayments into small daily amounts instead, matching the natural rhythm of daily sales and footfall. Working capital doesn’t take one big hit at the end of the month.
The underwriting system pays close attention to how well an account is managed day to day. It reviews 6 months of bank statements looking for clean habits, not red flags.
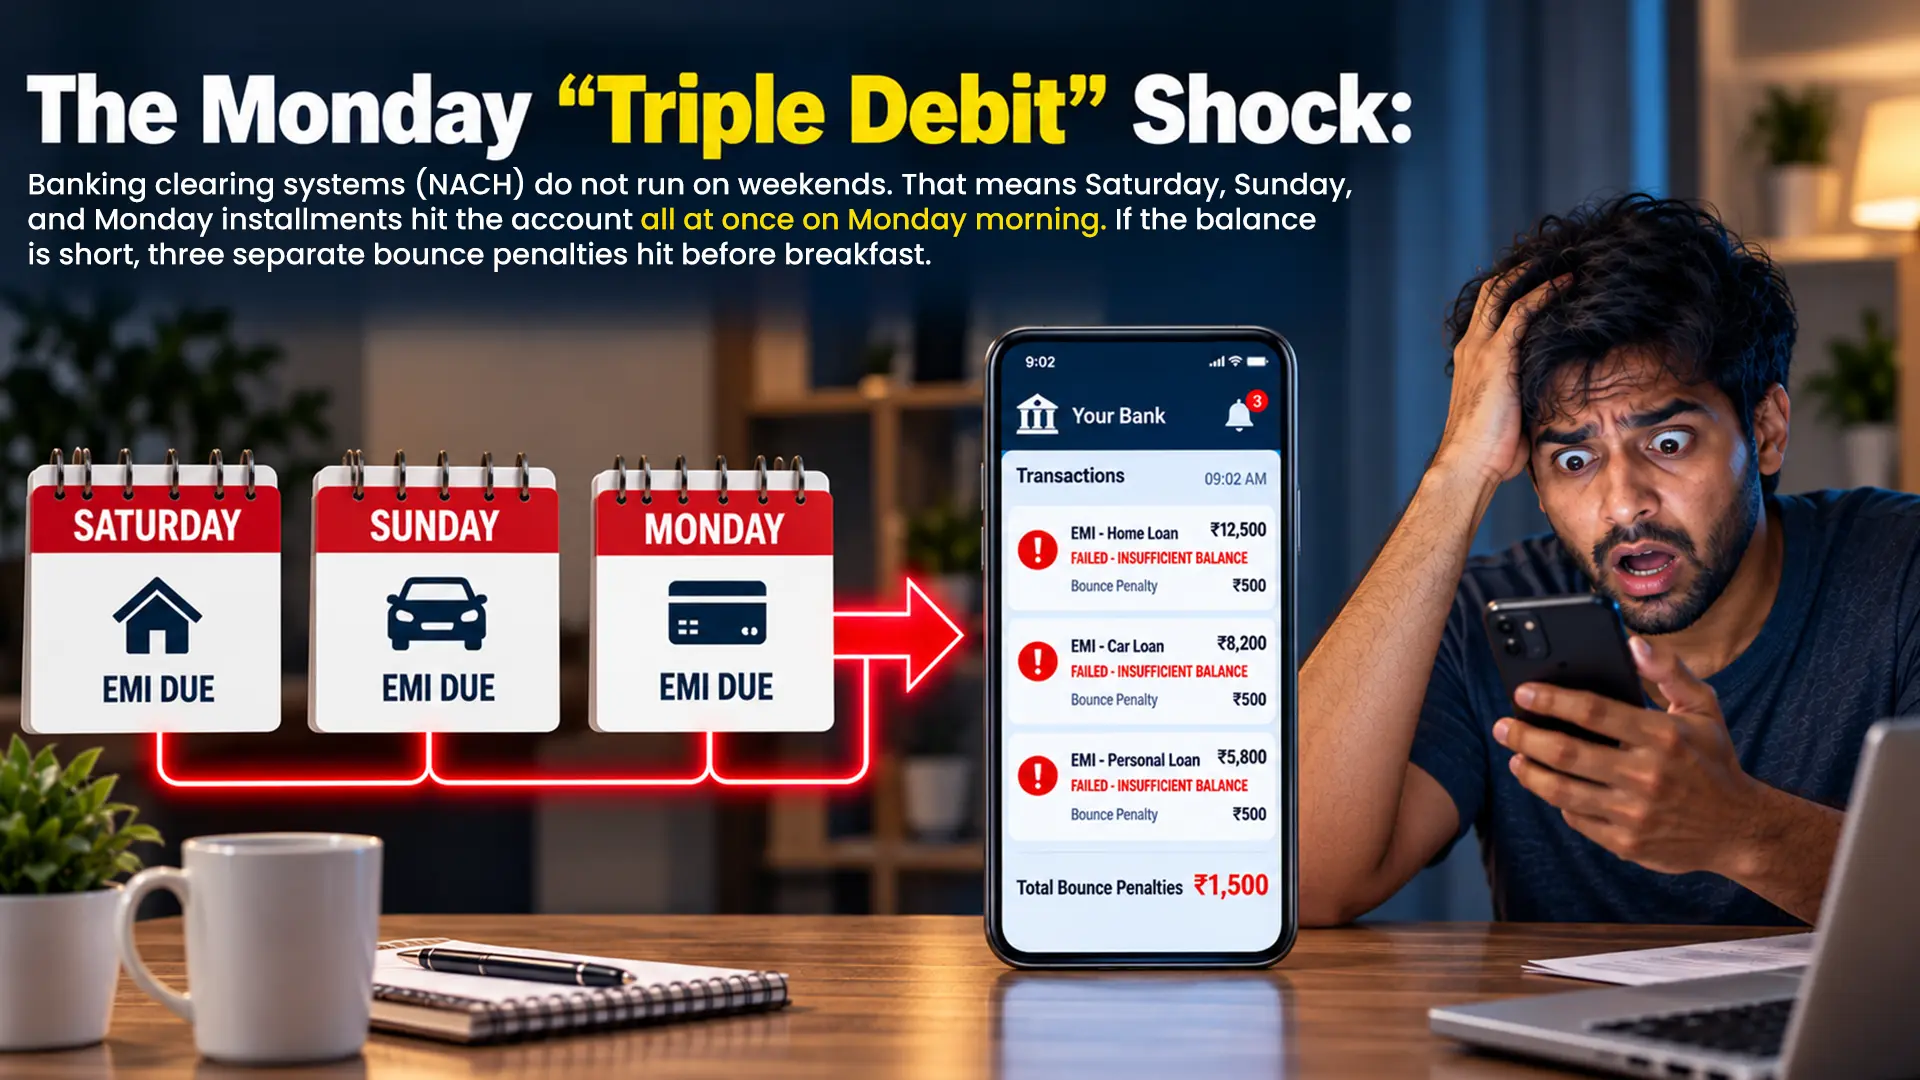
Banking Behaviour: The policy considers bounce history, including total bounces in the last 180 days, EMI bounces in the last 180 days, total bounces in the last 90 days, and EMI bounces in the last 90 days.
Picking the right loan structure changes what you end up paying overall. A business loan in India usually means choosing between a traditional collateral backed setup and a newer, fully digital option.
| Evaluation Metric | Traditional | Finkeda |
| Collateral Requirements | Yes, property, inventory, or gold has to be pledged. | No collateral, no co-borrower |
| Interest Rate Parameters | Varies, often tied to how the asset is valued | Rate of Interest: 28% on an annualized basis |
| Processing Fees and Costs | Can vary a lot, sometimes with hidden valuation charges | Transparent, capped at up to 3% |
| Verification Architecture | Manual audits and physical asset checks | Fully digital, based on bank statement analysis |
| Repayment Structures | Long term, often spread across years | Short term, 104 to 373 days |
Fast, predictable, and transparent credit is frequently what separates a struggling local business from one that is expanding. Understanding what a business loan entails, keeping your banking record clean, and preparing the required documents will put your company in a much better long-term position.
The partnership between Finkeda and Muthoot FinCorp has made obtaining an unsecured business loan in India significantly easier. Self-employed professionals can apply for funding between ₹50,000 and ₹1,000,000 at a fixed 28% annual rate. The entire process is completed digitally.
Processing fees are limited to 3%, and no physical verification is required. Daily EDI repayments make things easier to manage. This means less time spent on paperwork and more time dedicated to running your business.
A business loan is debt provided by banks, NBFCs, or digital lenders for business purposes, whether that’s daily operations, expansion, stocking inventory, or covering working capital.
Self employed individuals and shop owners aged 21 to 60, with at least 2 years running their business and a CIBIL score of 650 or higher, are eligible. You’ll need digital identity proof like Aadhaar and PAN, proof of business registration, and at least 6 months of bank statements.
You can apply online through platforms like the Finkeda Prime App. Fill out the digital form, upload 6 months of bank statements, and go through a quick video KYC plus a Video Personal Discussion. No physical visit needed.
A score of 650 or above clears the basic bar, and automated checks look at the rest. Keeping overdue amounts under ₹5,000, avoiding settlements in the past year, and staying under 3 credit inquiries in the last 30 days all help your application move faster.
They act as a buffer for daily costs. Equated Daily Installments spread across tenures of 104 to 373 days let owners manage short term needs without putting too much pressure on their finances.
Secured loans need collateral, like property or gold, and their rates shift depending on asset value. Unsecured digital loans skip collateral and co borrowers entirely, offering fast processing based on bank statement analysis and a fixed rate, in this case 28% annually.
Disclaimer: This article is for general informational purposes only and should not be considered financial or lending advice. Loan amount, interest rate, processing fees, eligibility criteria, repayment tenure, documentation requirements, approval, and disbursal are subject to the applicant’s profile and the applicable terms and conditions of the lending partner. Finkeda facilitates access to available financial products, while the final credit decision and loan terms are determined by the respective lending partner. Please verify the latest details and applicable terms before applying.
This blog is intended solely for educational and informational purposes. Content reflects data at time of publication and may not accurately reflect current premiums, terms, or regulations. Readers are encouraged to confirm the accuracy and relevance of the data before making any significant decisions.
Share :
Like:
0